


Saudi Arabia Construction Market Size, Share, Growth Trends & Forecast 2026-2034
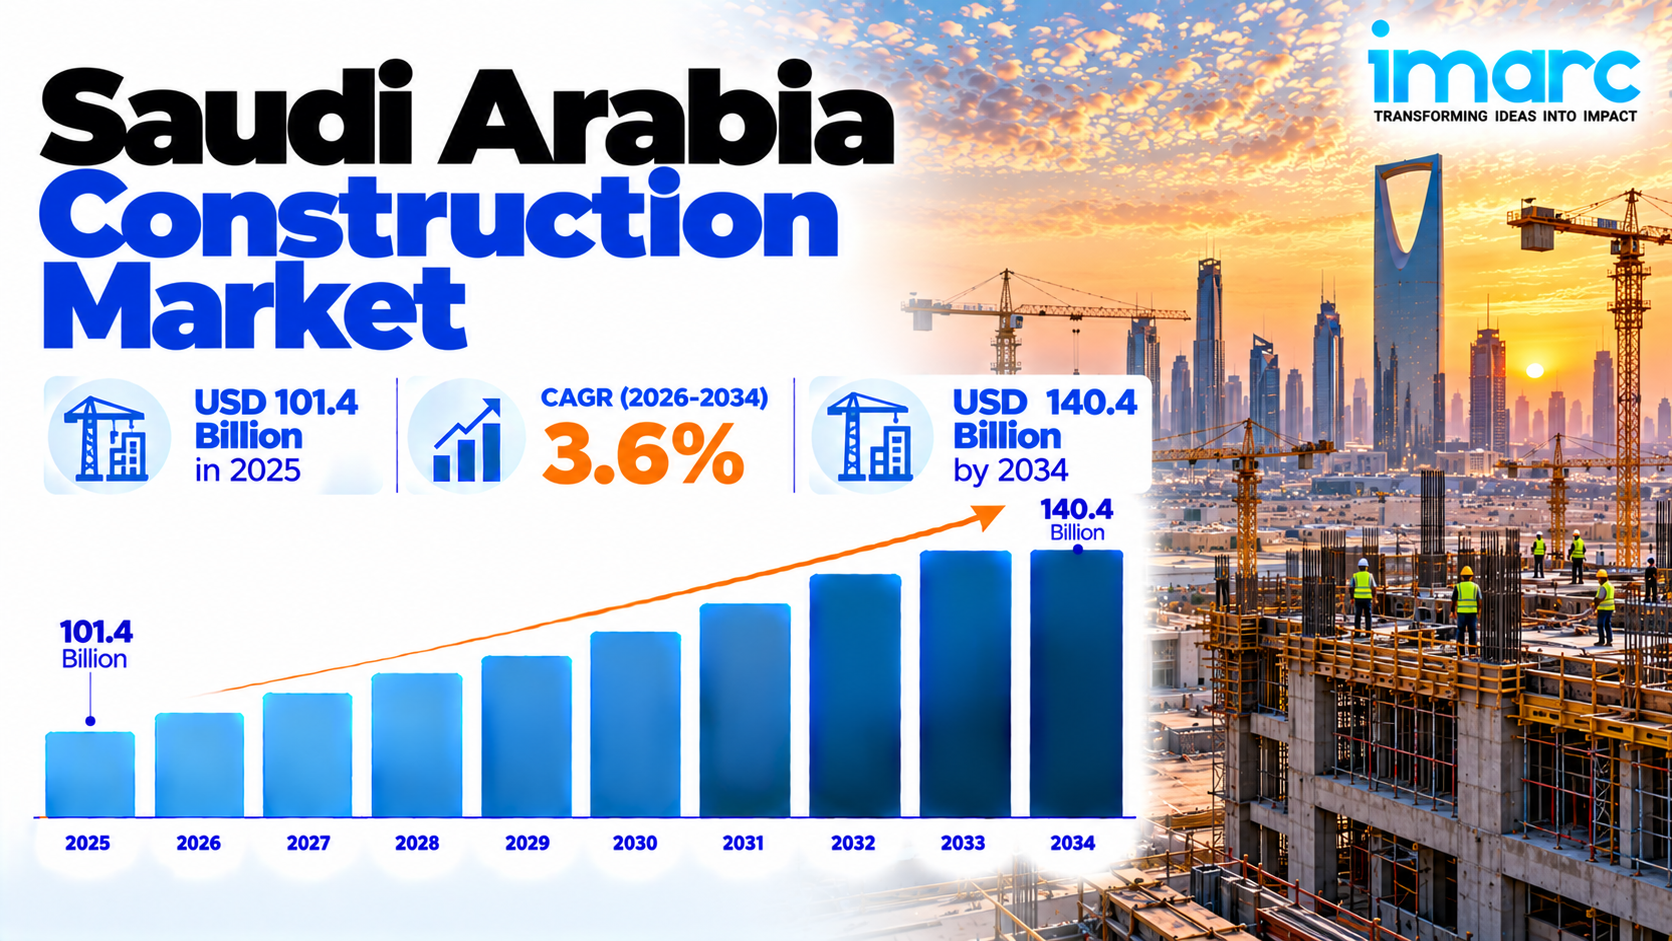
IMARC Group, a leading global market research and management consulting firm, has published its latest market intelligence report on the Saudi Arabia construction market. The Saudi Arabia construction market size was valued at USD 101.4 Billion in 2025, and is projected to reach USD 140.4 Billion by 2034, exhibiting a CAGR of 3.6% during 2026-2034, driven by Vision 2030 giga-project investments, robust government spending on housing and infrastructure, expanding tourism development, and a growing private sector role in commercial construction.
Construction benefits from the capital intensive nature of Vision 2030 execution in Saudi Arabia, with giga-projects, housing programs, and tourism infrastructure requiring continuous engineering, procurement, and construction activity across every phase of delivery. The market is forecast to add approximately USD 39 Billion in incremental value between 2025 and 2034, with three structural forces shaping this trajectory: the Kingdom's trillion dollar giga-project pipeline, the national shift toward renewable energy infrastructure, and a tourism construction boom tied to the Kingdom's visitor target.
Saudi Arabia Construction Market at a Glance:
- Market Size (2025): USD 101.4 Billion
- Forecast Market Size (2034): USD 140.4 Billion
- CAGR (2026-2034): 3.6%
- Leading Sector (2025): Residential, 42.5% share
- Leading Region (2025): Western Region, 38.6% share
- Fastest-Growing Segment: Energy and Utilities Construction, approximately 4.2% CAGR
How AI is Reshaping the Future of the Saudi Arabia Construction Market
- BIM-Driven Design and Coordination: Building Information Modelling is mandated for major public projects, with flagship developments leaning on integrated design-to-build workflows that cut design conflicts and rework costs across large-scale residential and infrastructure builds.
- Drone and AI-Powered Site Management: AI-powered project management platforms are now standard across mega-project sites, while drone-based surveillance reduces manual inspection costs on sprawling, multi-hundred-kilometre project footprints.
- Modular and Off-Site Manufacturing: Developers are piloting volumetric modular and prefabricated panel systems to accelerate housing delivery, with plans underway to industrialize construction component manufacturing within dedicated project zones.
Grab a sample PDF of this report: https://www.imarcgroup.com/saudi-arabia-construction-market/requestsample
Saudi Arabia Construction Market Trends and Drivers:
The Saudi Housing Program's target to raise homeownership from 47% to 70% by 2030 is the foundational driver behind Residential's dominant share of market revenue, generating continuous procurement demand across newly planned villas, apartment complexes, and affordable housing communities nationwide. A leading residential developer's pledge to invest well over three hundred billion riyals over the coming decade, building communities for more than a million and a half residents, underscores the scale of execution still ahead. The Western Region leads geographically on the back of Grand Mosque expansion work in Makkah, the Prophet's Mosque development in Madinah, and Jeddah's waterfront mega-projects, which together concentrate the Kingdom's highest construction density.
Energy and Utilities construction is emerging as the fastest-growing segment as the Kingdom works toward generating half of its electricity from renewable sources, expanding total capacity to well over a hundred gigawatts across solar, wind, and green hydrogen. Flagship projects such as a multi-gigawatt solar PV development and a green hydrogen complex tied to the Kingdom's northern giga-project are reshaping the construction pipeline away from oil-dependent infrastructure and toward clean energy systems, a shift expected to define contractor capability requirements through the rest of the decade.
Tourism and hospitality infrastructure is compounding this residential and energy led growth with a new high-value commercial construction category. The sector is targeted to contribute a tenth of GDP, requiring hundreds of thousands of additional hotel keys alongside resort, entertainment, and retail infrastructure tied to flagship coastal and heritage developments. Strong foreign direct investment inflows are reinforcing this momentum, fuelling commercial and industrial construction within dedicated economic zones, while the Kingdom's local content requirements are simultaneously incentivizing international and domestic contractors alike to deepen their Saudi manufacturing and supply footprint.
Government Schemes and Vision 2030 Initiatives Driving Demand:
- Giga-Project Investment Pipeline: A trillion dollar commitment to strategic projects, including the Kingdom's flagship northern mega-project, the Red Sea coastal development, and the Diriyah heritage gateway, is transforming the construction demand landscape at an unprecedented scale.
- Saudi Housing Program Homeownership Target: A core Vision 2030 program targeting a rise in homeownership from 47% to 70% by 2030, generating sustained procurement demand for residential delivery across every region of the Kingdom.
- National Renewable Energy Program: A commitment to generate half of the Kingdom's electricity from renewable sources by 2030, driving large-scale construction of solar parks, wind farms, and green hydrogen facilities under the clean energy transition agenda.
- Tourism and Hospitality Investment Pipeline: Vision 2030's tourism initiatives are underpinning coastal and heritage mega-developments and a sweeping hotel-key expansion, generating one of the largest hospitality construction cycles in the Kingdom's history.
- Smart Cities and Digital Construction Program: Government-backed smart city initiatives spanning Riyadh, Jeddah, and the Kingdom's northern giga-project are creating demand for construction-integrated ICT infrastructure, smart utilities, and building automation systems.
Saudi Arabia Construction Industry Segmentation:
The report has segmented the market into the following categories:
Breakup By Sector:
- Residential
- Commercial
- Industrial
- Infrastructure (Transportation)
- Energy and Utilities
Residential construction commands the leading 42.5% share of market revenue, reflecting sustained demographic pressure and government-backed homeownership and affordable housing targets. Commercial construction follows, supported by hotel, resort, and mixed-use development tied to tourism expansion, while Industrial and Infrastructure construction remain closely linked to Aramco and SABIC-driven industrial corridors. Energy and Utilities construction, though a smaller share today, is growing fastest as renewable capacity additions accelerate across the forecast period.
Breakup By Region:
- Western Region
- Eastern Region
- Northern and Central Region
- Southern Region
The Western Region commands the largest share of market revenue, anchored by Makkah, Madinah, and Jeddah's tripartite construction hub and the ongoing Grand Mosque expansion, among the world's largest construction projects by value. The Eastern Region follows on sustained oil and industrial infrastructure activity around Dammam and Jubail, while the Northern and Central Region, home to the Kingdom's flagship northern giga-project and the capital's growth corridor, stands out as the most strategically significant growth zone looking ahead. The Southern Region, though the smallest today, offers disproportionate growth runway as tourism upliftment programs unlock previously underserved demand.
Competitive Landscape:
The Saudi Arabia construction market features a mixed competitive structure of global EPC leaders, multinational engineering firms, and established regional contractors. The report provides detailed profiles of all major companies, including:
- Bechtel Corporation
- Fluor Corporation
- Jacobs
- Tekfen Construction
- Gilbane Inc.
- AFRAS
- AL Jazirah Engineers and Consultants
- Al-Latifia Trading and Contracting
Global leaders leverage deep EPC expertise and longstanding government relationships to secure the largest Aramco and giga-project contracts, while mid-tier challengers maintain strong positions in industrial and institutional construction. No single company dominates total market revenue, and consolidation is emerging as developers increasingly favor contractors capable of integrated project delivery across multiple value chain stages at once.
Market Concentration Analysis:
- Fragmentation: The market is moderately fragmented at the national level, with the leading players collectively accounting for a modest share of total construction value
- Segment Leadership: Global EPC leaders dominate large-scale giga-project delivery, while regional contractors maintain strong footholds in residential and institutional construction
- Consolidation Trend: International firms are increasingly entering through minority stakes in local contractors, enabling compliance with localization mandates while securing preferred contractor status
What Does The Full Report Cover?
If you are tracking the Saudi Arabia construction market for investment decisions, market entry planning, competitive benchmarking, or strategic advisory, IMARC Group's report gives you everything in one place:
- Complete market sizing in value terms with forecasts covering the full projection period
- Quantified growth driver analysis with impact scoring across sector and regional markets
- Sub-segment breakdowns for five sectors and four regions, each with individual share data
- Competitive profiles of leading EPC contractors and regional challengers with strategic positioning analysis
- Value chain analysis, market concentration assessment, and technology landscape coverage across design, engineering, and site management
- Latest trends covering BIM adoption, modular and off-site construction, renewable energy infrastructure, and smart city integration shaping market competition across the Kingdom
Recent News and Developments in Saudi Arabia Construction Market
- 2025: A leading global EPC contractor signed an agreement to serve as delivery partner for new terminals at a major Riyadh airport development.
- 2025: A global professional services firm confirmed its advisory role on a net-zero data center initiative within the Kingdom's northern giga-project.
- 2024: Industry trackers confirmed a wave of giga-project contract awards spanning hotel and mixed-use schemes, a pipeline expected to boost future construction orders across the Kingdom's hospitality and residential segments.
Note: If you require specific details, data, or insights that are not currently included in the scope of this report, we are happy to accommodate your request. As part of our customization service, we will gather and provide the additional information you need, tailored to your specific requirements. Please let us know your exact needs, and we will ensure the report is updated accordingly to meet your expectations.
Key Questions This Report Answers
- What is the current Saudi Arabia construction market size and what is its projected value?
- Which sector and region hold the largest share in the Saudi Arabia construction market?
- What are the key drivers of Saudi Arabia construction market growth?
- Which region dominates the Saudi Arabia construction market and which is growing fastest?
- How is Vision 2030's giga-project pipeline and renewable energy program reshaping the Saudi Arabia construction industry?
- Who are the top companies in the Saudi Arabia construction market and what are their competitive strategies?
- What are the investment and market entry opportunities across residential, energy, and tourism-linked construction in Saudi Arabia?
About Us
IMARC Group is a global management consulting firm that helps the world's most ambitious changemakers to create a lasting impact. The company provides a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
Media and Sales Contact
IMARC Group
Email: sales@imarcgroup.com
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Russian
 Romaian
 Portuguese (Brazil)
 Greek
 Bengali