


Data Center Semiconductor Market Size & Forecast 2025-2034
Market Overview
According to Dimension Market Research, the Global Data Center Semiconductor Market size is projected to reach USD 252.2 billion in 2025 and grow at a compound annual growth rate of 22.9% to reach a value of USD 1,613.9 billion in 2034. The market is witnessing explosive growth due to the rapid shift toward AI, cloud computing, big data analytics, and distributed edge infrastructure, driving demand for chips that offer higher parallel processing, increased bandwidth, low latency, and better energy efficiency.
The data center semiconductor market encompasses a wide range of chips powering modern data infrastructure—processors, memory, storage controllers, networking silicon, and power/analog ICs. These components are central to enabling compute, storage, networking, power management, and security functions across traditional enterprise setups and modern hyperscale environments.
Demand is being driven by a rapid shift toward AI, cloud computing, big data analytics, and distributed edge infrastructure. As workloads grow more specialized and intensive, data centers require chips that offer higher parallel processing, increased bandwidth, low latency, and better energy efficiency. This is fueling growth in advanced processors, accelerators, and high-performance memory systems.
Architectural innovation is accelerating beyond legacy server designs, with greater adoption of GPUs, ASICs, FPGAs, and custom silicon. Meanwhile, memory and storage subsystems are being reengineered to meet real-time processing needs, while networking and power management ICs ensure system scalability and rack-level efficiency in disaggregated, modular topologies.
Definition and Market Significance
Data center semiconductors are specialized integrated circuits designed to power modern data infrastructure, including processors, memory, storage controllers, networking chips, power management ICs, and analog/mixed-signal semiconductors. These components enable compute, storage, networking, power management, and security functions across enterprise, hyperscale, cloud, and telecom data centers.
The importance of data center semiconductors lies in their foundational role in enabling digital transformation, AI workloads, cloud services, and big data analytics. As data volumes grow exponentially and workloads become more complex, advanced semiconductors are essential for delivering the performance, efficiency, and scalability required by modern data centers.
Data center semiconductors also support broader technological and economic objectives by enabling innovation in AI, machine learning, real-time analytics, and edge computing, driving productivity gains and competitive advantage across industries.
Request a Complimentary PDF Sample
https://dimensionmarketresearch.com/request-sample/data-center-semiconductor-market/
Market Drivers
A major factor driving the Data Center Semiconductor Market is the explosion of AI and workload expansion. The explosion of generative AI, deep learning, and large‑scale inference/training workloads is forcing data centers to upgrade semiconductor architectures. High‑performance GPUs, ASICs and accelerators are increasingly required for parallel compute, pushing demand for semiconductors optimized for throughput, bandwidth and power efficiency. As software models get larger and more complex, hardware must evolve rapidly, driving semiconductor adoption in compute, memory and networking.
Cloud and edge infrastructure growth is another key driver supporting market expansion. The expansion of hyperscale cloud data centers, along with the growing importance of edge computing and distributed data‑center footprints, is prompting operators to deploy more advanced semiconductors to manage latency, interconnect, power density and scalability. Telecom, IoT, and mobile workloads expanding into edge nodes further amplify demand for data‑center grade semiconductors outside conventional facilities.
The increasing demand for higher performance-per-watt, lower latency, and greater energy efficiency is also contributing to market growth, as data center operators seek to reduce operational costs and meet sustainability targets.
Market Trends
The shift toward heterogeneous compute and accelerators is emerging as an important trend in the data center semiconductor market. Traditional CPU‑centric architectures are giving way to heterogeneous systems incorporating GPUs, FPGAs, ASICs and AI‑specific accelerators for higher efficiency in data‑center workloads, particularly AI.
Another significant trend is the rise of packaging and chip‑let integration. To meet performance/per‑watt demands and reduce costs, advanced packaging (3D stacking, chiplets, integrated interposers) is becoming more mainstream in data‑centre semiconductors. This enables faster deployment of highly‑customised semiconductor modules for AI clusters and high‑density racks.
The integration of AI and machine learning for smarter power management, cooling subsystems, and dynamic load balancing is also transforming the market, driving demand for power and analog semiconductors optimized for dynamic workloads.
Market Restraints
Despite its strong growth potential, the Data Center Semiconductor Market faces certain limitations. Node migration and manufacturing complexity pose significant challenges. Advanced process nodes and packaging techniques (e.g., 3D stacking, chiplets) are required to deliver next‑generation performance and efficiency. However, migrating to <7nm or advanced packaging increases cost, development time and supply‑chain risk, hampering some adoption.
Supply‑chain and geopolitical constraints are another significant restraint. The semiconductor ecosystem is subject to constrained foundry capacity, export controls, and regionalisation pressures. These factors affect availability of high‑end chips (especially GPUs and accelerators) for data centers, delaying roll‑out and increasing cost.
In addition, margin compression across chip types and the need for continuous investment in R&D and manufacturing capacity can affect profitability and market growth.
Market Opportunities
Specialized accelerators and domain‑specific chips present significant growth opportunities. As operators seek efficiency gains and differentiation, the design and deployment of ASICs and disaggregated accelerator chips tailored to workloads (e.g., inference, memory bandwidth) represent big growth opportunities for chipset vendors.
Memory/compute disaggregation and interconnect innovation is another promising opportunity. Emerging architectures such as CXL (Compute Express Link), memory pooling, high‑bandwidth memory (HBM), photonic interconnects and modular data‑center racks create opportunities for new semiconductor solutions across memory, networking and power domains.
Furthermore, the expansion of AI-as-a-Service (AIaaS), edge computing, and sovereign data center initiatives is expected to open new opportunities for data center semiconductor providers.
Segmentation
The Data Center Semiconductor Market is categorized based on component type, function, technology node, and application.
By component type, processors account for 43.5% of the total market in 2025, reflecting their indispensable role in powering compute-intensive operations. The category includes CPUs for general-purpose compute, GPUs for parallel workloads, ASICs for specialized tasks like AI inference, and FPGAs for workload flexibility. Memory is the fastest-growing segment, driven by the explosion of data and increasing demand for higher storage speed and lower latency.
By function, the compute function leads with an estimated 46.2% share in 2025. This segment encompasses the processors and memory elements that execute and support critical workloads, including AI model training, big data analytics, and virtualized computing. Networking is the fastest-growing function segment, powered by increasing demand for data movement between compute nodes, storage units, and cloud edges.
By technology node, the 14nm technology node leads with a share of 41.8% in 2025, mainly due to its maturity, reliability, and cost-effectiveness for mainstream server components. Sub-7nm nodes are the fastest-growing technology segment as demand intensifies for more powerful and energy-efficient chips.
By application, hyperscale data centers dominate with approximately 48.9% of semiconductor demand in 2025. These massive facilities operated by tech giants and cloud providers require continuous upgrades in processing, memory, storage, and networking capabilities. Cloud Service Providers (CSPs) are the fastest-growing end-user category, driven by rapid digital transformation and the shift toward scalable, on-demand infrastructure.
Regional Analysis
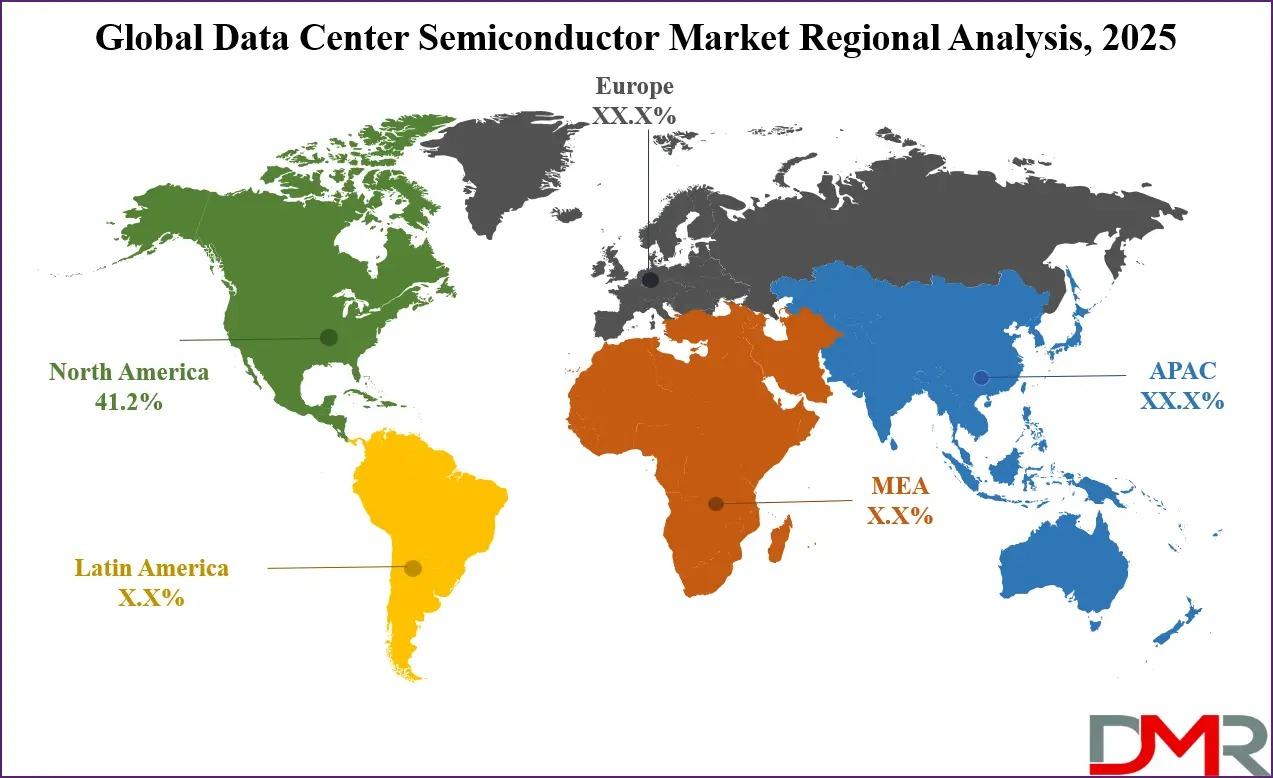
North America stands as the leading region in the data center semiconductor market in 2025, accounting for approximately 41.2% of the global share. This dominance is anchored by the presence of major hyperscale cloud providers, AI research hubs, and advanced semiconductor firms. The region hosts some of the world's largest data centers, operated by cloud and tech giants, driving continuous investment in cutting-edge chips for compute, memory, networking, and storage. The US market is projected to reach USD 87.0 billion in 2025 at a CAGR of 21.5%.
Europe holds a substantial share of the data center semiconductor market, projected to reach USD 55.5 billion in 2025 at a CAGR of 20.2%. In Europe, the semiconductor-data-center ecosystem is evolving under a dual constraint: strong regulatory and sustainability frameworks, combined with rising demand for high‑performance infrastructure. European governments and the EU as a bloc are committing major funds to build AI data centers and support semiconductor manufacturing capacity.
Asia Pacific is the fastest-growing region in the global data center semiconductor market, driven by rapid digital transformation, rising cloud adoption, and increasing investments in hyperscale and telecom data centers. Countries like China, India, South Korea, and Singapore are expanding their data infrastructure to meet growing demand from AI services, 5G, and data localization policies. Japan's market is projected to reach USD 15.1 billion in 2025 at a CAGR of 23.3%.
Latin America and the Middle East & Africa are gradually adopting data center semiconductor solutions as digital infrastructure expands and cloud adoption increases, with Brazil, Mexico, the UAE, and Saudi Arabia emerging as key markets.
Competitive Landscape
The competitive landscape in the data‑center semiconductor market is characterized by major manufacturers of processors, memory and networking semiconductors, as well as niche accelerator and power/analog suppliers. Leading semiconductor firms design and supply server CPUs, GPUs, and accelerators for hyperscale cloud data‑centers, often in collaboration with cloud service providers and foundries. Specialist chip firms focus on domain‑specific accelerators and high‑bandwidth memory or networking silicon.
Prominent players include Intel Corporation, Advanced Micro Devices (AMD), NVIDIA Corporation, Broadcom Inc., Qualcomm Technologies Inc., Samsung Electronics Co., Ltd., Micron Technology, Inc., SK hynix Inc., Taiwan Semiconductor Manufacturing Company (TSMC), Marvell Technology, Inc., Texas Instruments Incorporated, Infineon Technologies AG, Analog Devices, Inc., NXP Semiconductors N.V., Microchip Technology Inc., Renesas Electronics Corporation, Western Digital Corporation, Kioxia Corporation, Seagate Technology Holdings plc, Arm Holdings plc, and IBM Corporation. Recent developments include NVIDIA and TSMC's unveiling of the first "Blackwell" AI‑chip wafer manufactured in the United States (October 2025) and GlobalFoundries' raised investment plan to support emerging semiconductor technologies (June 2025).
Technological Advancements
Rapid advancements in advanced process nodes, chiplet architectures, high-bandwidth memory, and photonic interconnects are transforming the data center semiconductor market. Chips at sub-7nm nodes deliver significantly higher transistor density, better performance-per-watt, and superior integration capabilities, ideal for handling complex AI inference, real-time analytics, and dynamic multi-tenant workloads.
The integration of AI and machine learning for smarter power management, cooling subsystems, and dynamic load balancing is also playing a significant role, driving demand for power and analog semiconductors optimized for dynamic workloads.
Consumer Adoption Patterns
Hyperscale data centers, enterprise data centers, cloud service providers, and telecom data centers are increasingly adopting advanced data center semiconductors to support AI training, big data analytics, cloud services, and real-time applications. The growing availability of custom silicon, high-bandwidth memory, and advanced networking chips is driving adoption across all facility types.
Regulatory Environment
Regulatory frameworks across different regions, including export controls, domestic manufacturing incentives such as the CHIPS Act, and data sovereignty requirements, significantly influence the data center semiconductor market. Compliance with these regulations and access to government incentives are key factors for market participants.
Market Challenges
The data center semiconductor market faces challenges related to manufacturing complexity at advanced nodes, supply chain constraints, geopolitical tensions, margin compression, and the need for continuous investment in R&D and manufacturing capacity. Additionally, the rapid pace of technological change requires companies to continuously innovate to remain competitive.
Future Outlook
The future of the Data Center Semiconductor Market remains exceptionally promising as AI, cloud computing, and edge infrastructure continue to drive demand for advanced semiconductors. Increasing adoption of heterogeneous compute architectures, advanced packaging, high-bandwidth memory, and custom silicon, along with government support for domestic manufacturing, are expected to drive strong market growth during the forecast period, with the market projected to reach USD 1,613.9 billion by 2034 at a CAGR of 22.9%.
FAQs
What is the expected size of the Data Center Semiconductor Market in 2025?
The market is expected to reach USD 252.2 billion in 2025.
What is the projected market value by 2034?
The market is forecast to reach USD 1,613.9 billion by 2034.
What is the CAGR of the Data Center Semiconductor Market?
The market is expected to grow at a CAGR of 22.9% during 2025–2034.
Which technology node segment dominates the market?
The 14nm technology node leads with a share of 41.8% in 2025.
Which region leads the global data center semiconductor market?
North America is expected to hold 41.2% of the market share in 2025.
Summary of Key Insights
The global Data Center Semiconductor Market is expected to grow from USD 252.2 billion in 2025 to USD 1,613.9 billion by 2034, recording a CAGR of 22.9% during the forecast period. Processors lead the component type segment with 43.5% share, while the compute function leads with 46.2% share. The 14nm technology node dominates with 41.8% share, and hyperscale data centers lead applications with 48.9% share. North America holds the largest regional share with 41.2% of global revenue in 2025, while Asia Pacific is projected as the fastest-growing region. The US market is projected to reach USD 87.0 billion in 2025 at a CAGR of 21.5%.
Purchase the Full Report
https://dimensionmarketresearch.com/checkout/data-center-semiconductor-market/

 English
 Arabic
 French
 Spanish
 Portuguese
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek
 Bengali