


Aluminium Scandium Alloy Market: Geographic Market Share and Strategic Regional Analysis (2024–2031)
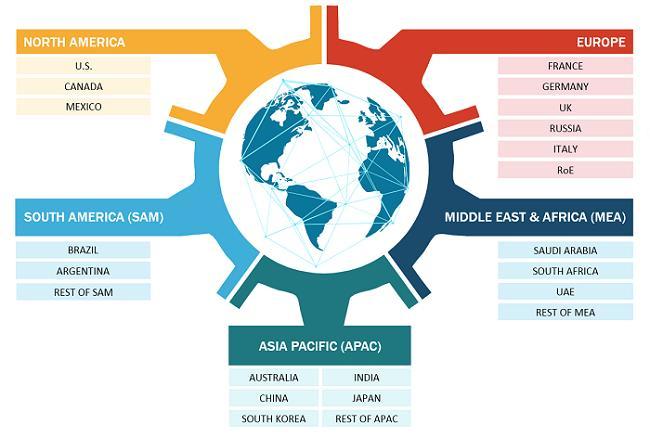
The global metallurgy and advanced materials sector is witnessing a transformative era as industries seek higher performance-to-weight ratios to meet sustainability and efficiency targets. Aluminium Scandium (Al-Sc) Alloy has emerged as one of the most potent solutions in this transition. By adding trace amounts of scandium to aluminium, manufacturers create a material that exhibits exceptional strength, superior weldability, and remarkable thermal stability. These alloys are effectively redefining the boundaries of structural engineering in the aerospace, defense, and high-performance automotive sectors.
According to strategic research from The Insight Partners, the global Aluminium Scandium Alloy Market is expected to register a significant CAGR from 2025 to 2031. Following a period of foundational growth in 2024, the market size is projected to expand substantially through 2031. This upward trajectory is fueled by the aggressive pursuit of "lightweighting" in transportation and the increasing commercial availability of scandium feedstock through diversified global supply chains.
Download Sample PDF Brochure: https://www.theinsightpartners.com/sample/TIPRE00012830
Market Share Analysis by Geography
The global distribution of the Aluminium Scandium alloy market is dictated by two primary factors: the location of specialized aerospace manufacturing hubs and the proximity to stable scandium extraction and purification facilities.
1. North America: The Innovation and Defense Hub
North America currently holds a dominant share of the global market, estimated at approximately 35%.
-
Key Drivers: The presence of aerospace giants like Boeing and Lockheed Martin, combined with massive U.S. defense spending on next-generation fighter jets and missile systems, sustains high demand.
-
Supply Chain Shift: Significant investments in domestic scandium recovery—such as Rio Tinto’s operations in Canada and NioCorp’s development in the U.S.—are positioning the region as a self-sufficient leader in the "mine-to-metal" lifecycle.
2. Europe: Advanced Manufacturing and Sustainability
Europe represents a significant market share, driven by a mature aerospace sector and stringent environmental regulations that prioritize fuel efficiency.
-
Key Drivers: Airbus is a major proponent of Al-Sc alloys, particularly for welded airframe structures. The region is also a pioneer in Scalmalloy® (a specialized Al-Sc-Mg powder) for high-end additive manufacturing.
-
Industrial Focus: European automotive manufacturers (e.g., in Germany and Italy) are increasingly adopting these alloys for high-performance Electric Vehicle (EV) components to optimize battery range.
3. Asia-Pacific: The High-Growth Powerhouse
The Asia-Pacific region is projected to register the highest CAGR through 2031.
-
Key Drivers: China is a global leader in both scandium oxide production and downstream aluminium smelting. The rapid expansion of China's commercial aviation sector (COMAC) and its world-leading EV market are massive catalysts for volume growth.
-
Regional Dynamics: Increasing aerospace manufacturing in India and advanced electronics/sporting goods production in Taiwan and South Korea contribute to the region’s expanding market share.
Strategic Market Report Drivers: Catalyzing the Significant CAGR
The expansion forecasted through 2031 is supported by three primary industrial catalysts that emphasize material performance and resource efficiency:
-
Microstructural Superiority: Scandium is the most effective grain refiner for aluminium. It prevents the recrystallization that typically weakens alloys during heating, making Al-Sc the only high-strength aluminium that can be reliably welded without losing structural integrity.
-
Synergy with Additive Manufacturing (3D Printing): As the aerospace industry moves toward 3D-printed parts, Al-Sc powders provide the thermal stability required to prevent "hot cracking" during laser melting, a common failure in traditional aluminium powders.
-
Supply Chain Stabilization: Transitioning from "rare earth" status to a more predictable industrial mineral (recovered as a by-product of titanium and nickel) has lowered the barrier to entry, making long-term industrial adoption economically viable.
Top Key Players in the Aluminium Scandium Alloy Market
-
Rio Tinto
-
RUSAL
-
Scandium International Mining Corp.
-
AMG Critical Materials
-
Clean TeQ Speciality Metals
-
Metallicloud
-
Stanford Materials Corporation
-
Alcoa Corporation
-
Platina Resources Limited
-
NioCorp Developments Ltd.
Conclusion: Strategic Outlook for 2031
By 2031, the Aluminium Scandium alloy market will have matured from a specialized niche into a cornerstone of the advanced materials industry. The expansion from 2024 levels reflects a broader industrial shift: the prioritization of extreme performance and resource efficiency. For stakeholders, the greatest potential lies in the integration of these alloys with Additive Manufacturing and Space Exploration infrastructure. As regional supply chains continue to stabilize, the "scandium effect" will become a standard requirement for any industry looking to achieve the next generation of lightweight engineering.
About Us
The Insight Partners is a one-stop industry research provider of actionable intelligence. We help our clients find solutions to their research requirements through our syndicated and consulting research services across sectors including Chemicals and Materials, Automotive, Aerospace and Defense, and Technology.
Contact Us
If you have any queries about this report or if you would like further information, please contact us:
-
Contact Person: Ankit Mathur
-
E-mail: sales@theinsightpartners.com
-
Phone: +1-646-491-9876
-
Address: 14th Floor, Amar Paradigm, Baner, Pune – 411045, India.

 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek
 Bengali