


Top Sources of Working Capital to Support Business Growth
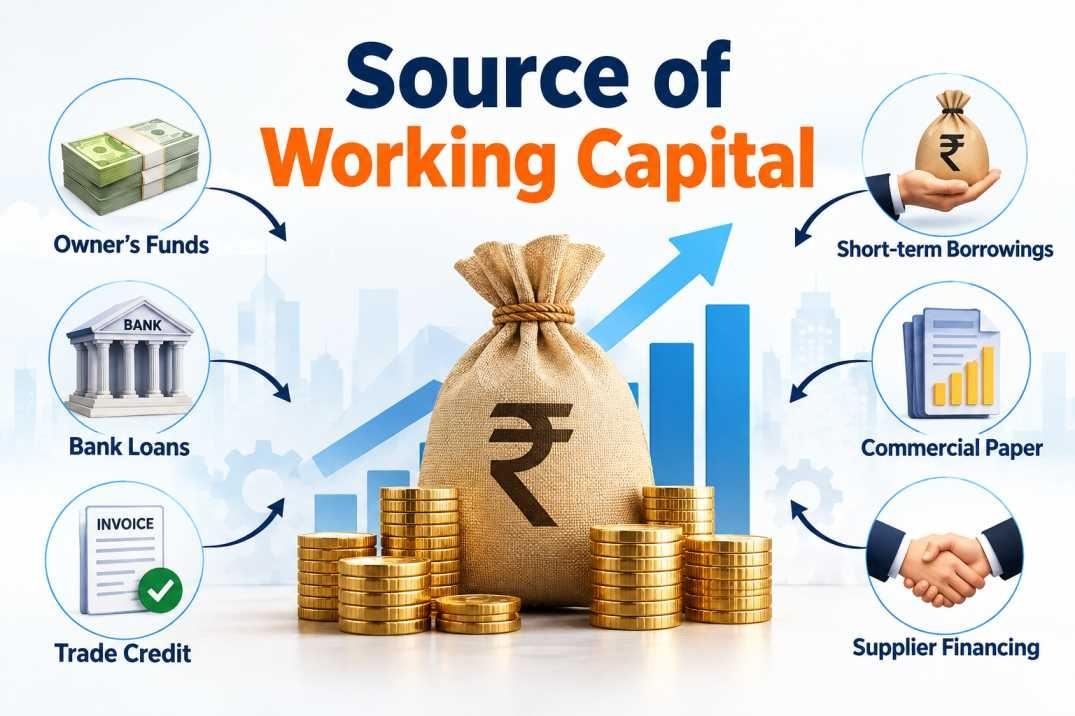
Working capital is essential for maintaining daily business operations, managing expenses, and supporting long-term growth. Businesses need sufficient funds to purchase inventory, pay employees, manage supplier payments, and handle unexpected expenses. Understanding the different sources of working capital helps business owners choose suitable financing options and maintain healthy cash flow.
Whether you operate a small business, a startup, or an established company, selecting the right source of working capital can improve financial stability and create opportunities for expansion.
What Is Working Capital?
Working capital refers to the difference between a company's current assets and current liabilities. It indicates whether a business has sufficient short-term resources to meet its immediate financial obligations.
The formula for working capital is:
Working Capital = Current Assets − Current Liabilities
Current assets include cash, accounts receivable, and inventory, while current liabilities include accounts payable and short-term debt. Maintaining adequate working capital helps businesses operate efficiently and respond to changing market conditions.
Top Sources of Working Capital for Businesses
1. Business Bank Loans
Business loans are one of the most common sources of working capital. Banks and financial institutions offer financing to eligible businesses for operational expenses, inventory purchases, supplier payments, and other short-term requirements.
Businesses can select loan amounts and repayment periods based on their financial needs and eligibility. However, it is important to compare interest rates, processing fees, repayment schedules, and other terms before applying.
2. Invoice Discounting
Invoice discounting allows businesses to access funds tied up in unpaid customer invoices. Instead of waiting for customers to pay, a business can use eligible invoices to obtain financing from a lender or financial service provider.
This option is particularly useful for businesses that sell products or services on credit and experience long payment cycles. Invoice discounting can improve liquidity while helping companies manage payroll, supplier payments, and everyday operational expenses.
Businesses should carefully review financing costs, invoice eligibility, and repayment conditions before choosing this solution.
3. Trade Credit from Suppliers
Trade credit enables businesses to purchase goods or services from suppliers and pay at an agreed future date. It helps companies maintain inventory and continue operations without making immediate payments.
For example, a retailer may purchase inventory with a 30-day payment term and use the products to generate sales before settling the supplier's invoice.
Strong supplier relationships and a reliable payment history can help businesses negotiate favourable credit terms. However, companies should avoid late payments that could damage supplier relationships or result in additional charges.
4. Business Overdraft Facilities
A business overdraft allows an eligible company to withdraw more money than its available account balance, up to an approved limit. It can provide short-term financial flexibility when cash inflows and outflows do not match.
Overdraft facilities are useful for managing temporary cash shortages, emergency expenses, and delayed customer payments. Businesses generally pay interest on the amount used, subject to the lender's terms and applicable fees.
5. Retained Earnings and Internal Funds
Retained earnings are profits kept within a business rather than distributed to owners or shareholders. Companies can use these funds to finance daily operations, purchase inventory, or support business expansion.
Using internal funds may reduce dependence on external borrowing and interest payments. However, businesses should maintain sufficient reserves for emergencies and avoid investing all available cash in a single activity.
6. Short-Term Business Financing
Short-term financing provides funds for immediate business requirements, usually with a defined repayment period. It may be suitable for purchasing seasonal inventory, covering temporary operating expenses, or managing a short-term gap between payments and receipts.
Before selecting a financing product, businesses should evaluate the total borrowing cost, repayment frequency, eligibility requirements, and potential impact on future cash flow.
7. Working Capital Financing from NBFCs and Financial Institutions
Non-banking financial companies (NBFCs) and other financial institutions may offer working capital products tailored to different business needs. Depending on the provider, these may include business loans, invoice-based financing, or other short-term credit facilities.
These options can provide an alternative to traditional bank financing. Businesses should compare the lender's credibility, applicable interest rates, fees, documentation requirements, and repayment conditions before making a decision.
How to Choose the Right Source of Working Capital
Choosing an appropriate source of working capital depends on the company's financial position, cash flow cycle, and operational requirements. Consider the following factors before selecting a financing option:
-
Business requirements: Estimate the amount needed and identify whether the requirement is temporary or ongoing.
-
Financing costs: Compare interest rates, processing fees, service charges, and the total repayment amount.
-
Repayment capacity: Ensure that expected cash inflows can cover repayments without disrupting business operations.
-
Funding speed: Consider how quickly the funds are needed and the time required for approval and disbursement.
-
Eligibility criteria: Review credit history, business turnover, documentation, and any collateral requirements.
-
Financial flexibility: Choose an option that supports operations without creating excessive debt or cash flow pressure.
A well-planned financing strategy helps businesses meet their current obligations while preserving resources for future growth.
Benefits of Maintaining Adequate Working Capital
Maintaining sufficient working capital offers several advantages for businesses.
Smooth Daily Operations
Adequate funds help companies pay employees, purchase inventory, settle supplier invoices, and manage routine expenses on time.
Improved Cash Flow Management
Access to suitable financing can help businesses manage delayed customer payments and seasonal changes in revenue.
Better Supplier Relationships
Timely payments can strengthen supplier relationships and improve opportunities to negotiate favourable purchasing terms.
Support for Business Expansion
Sufficient working capital allows businesses to respond to increased demand, introduce new products, and explore new markets without unnecessarily disrupting existing operations.
Greater Financial Stability
A suitable working capital reserve helps businesses manage unexpected expenses and reduce the risk of short-term liquidity problems.
Common Mistakes to Avoid When Arranging Working Capital
Businesses should avoid borrowing more than they can comfortably repay. They should also assess the total cost of financing instead of focusing only on the advertised interest rate.
Other common mistakes include relying heavily on short-term debt for long-term investments, ignoring overdue customer invoices, maintaining excessive inventory, and failing to prepare cash flow forecasts.
Regularly reviewing receivables, payables, inventory levels, and upcoming financial commitments can help business owners identify funding gaps early and make informed decisions.
Conclusion
Understanding the top sources of working capital helps businesses manage daily expenses, maintain liquidity, and support sustainable growth. Business loans, invoice discounting, supplier credit, overdraft facilities, retained earnings, and financing from financial institutions can each serve different operational needs.
The best option depends on the business's cash flow cycle, funding requirements, repayment capacity, and overall financial strategy. By comparing available options and planning ahead, businesses can strengthen financial management, reduce cash flow disruptions, and build a stable foundation for long-term success.
Frequently Asked Questions
What are the main sources of working capital?
The main sources include business loans, invoice discounting, trade credit, overdraft facilities, retained earnings, short-term financing, and funding from financial institutions.
Which source of working capital is suitable for small businesses?
The right option depends on the business's financial position and funding needs. Small businesses may consider supplier credit, internal funds, invoice discounting, or suitable business loans after comparing costs and repayment terms.
How does invoice discounting help improve working capital?
Invoice discounting allows businesses to access funds against eligible unpaid invoices, helping them manage expenses without waiting for customers to complete their payment cycles.
Why is working capital important for business growth?
Working capital helps businesses cover daily expenses, maintain inventory, pay suppliers, manage cash flow, and take advantage of growth opportunities.
How can businesses improve their working capital position?
Businesses can improve working capital by collecting payments faster, managing inventory efficiently, negotiating supplier payment terms, controlling operating expenses, and choosing appropriate financing options.

 English
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek
 Bengali