


Automotive Glass Market 2026 | Industry Size, Share, Growth, Trends & Future Outlook Report by 2034
Market Overview
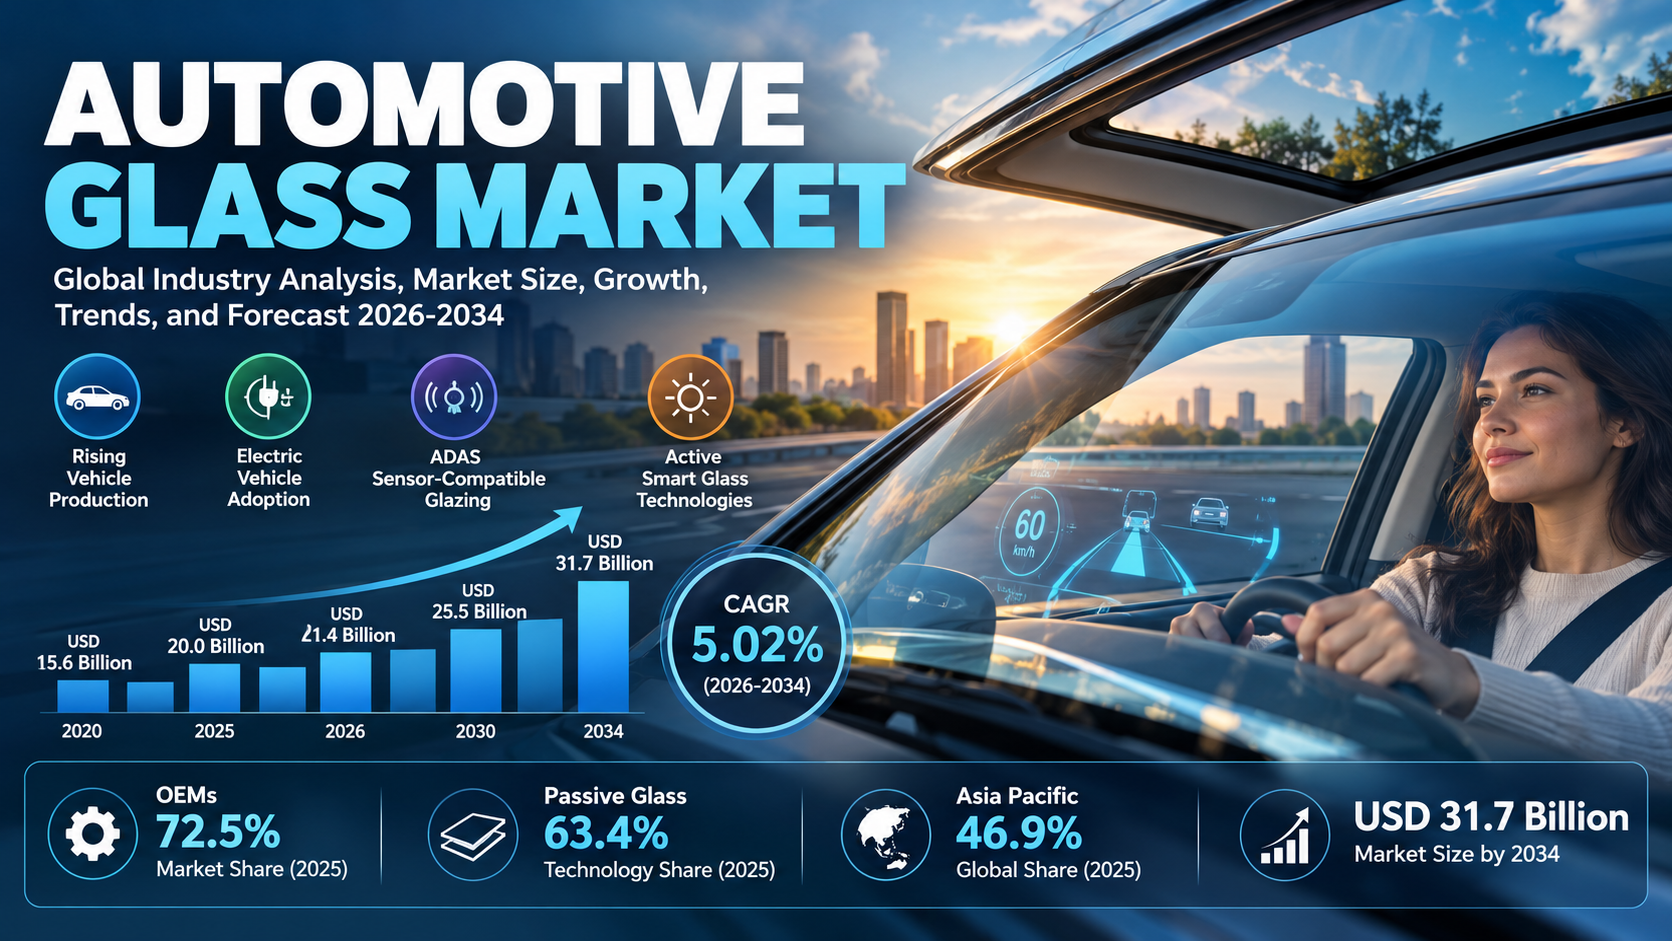
The global automotive glass market size is experiencing steady growth as vehicle production expands, electric vehicle adoption accelerates, and automakers increasingly integrate advanced glazing technologies into modern vehicles. The market reached USD 20.0 Billion in 2025 and is estimated to reach USD 21.4 Billion in 2026. According to the market assessment, it is projected to reach USD 31.7 Billion by 2034, expanding at a CAGR of 5.02% during 2026–2034.
The industry is being influenced by rising vehicle production volumes, increasing demand for electric vehicles, advanced driver assistance systems (ADAS), heads-up display (HUD) technologies, and the growing adoption of smart glass. Lightweight glazing, acoustic insulation, solar-control coatings, and sensor-compatible windshields are also creating new opportunities for automotive glass manufacturers.
Automotive Glass Market Snapshot
-
Base Year: 2025
-
Historical Period: 2020–2025
-
Forecast Period: 2026–2034
-
Market Size (2020): USD 15.6 Billion
-
Market Size (2025): USD 20.0 Billion
-
Market Size (2026): USD 21.4 Billion
-
Market Forecast (2030): USD 25.5 Billion
-
Market Forecast (2034): USD 31.7 Billion
-
CAGR (2026–2034): 5.02%
-
Leading Region: Asia Pacific
-
Dominant End-User Segment: Original Equipment Manufacturers (OEMs)
-
Dominant Technology Segment: Passive Glass
-
Leading Regional Market Share: Asia Pacific, with 46.9% in 2025
Asia Pacific accounted for 46.9% of the global automotive glass market in 2025, supported by its extensive automotive manufacturing infrastructure, expanding electric vehicle production, and strong presence of major glass manufacturers in China, Japan, South Korea, and India.
Request a Sample Report for Detailed Evaluation: https://www.imarcgroup.com/automotive-glass-market/requestsample
What Is Driving Automotive Glass Market Growth?
Rising Vehicle Production and Manufacturing Expansion
Increasing vehicle production is a key factor driving growth in the global auto glass market. Modern passenger cars and commercial vehicles incorporate multiple glazing components, including windshields, side windows, rear windows, and sunroofs. As automotive manufacturing expands worldwide, demand for standard and advanced automotive glass continues to rise across various vehicle categories.
Global vehicle production reached 92.5 million units in 2024, reflecting the continued recovery of the automotive industry from pandemic-related disruptions. This growth is creating opportunities for auto glass manufacturers to expand production capacity, strengthen supply chains, and develop innovative glazing solutions for passenger cars, commercial vehicles, trucks, and buses.
Automotive manufacturers are increasingly seeking high-performance glazing products that comply with stringent safety regulations while enhancing visibility, thermal efficiency, acoustic insulation, and vehicle aesthetics. In response, glass suppliers are investing in advanced manufacturing processes, including precision cutting, lamination, tempering, and specialized coating technologies. The growing integration of panoramic sunroofs, heated windshields, camera-compatible glass, and advanced optical glazing is further increasing the technological complexity and value of automotive glass systems.
Additionally, rising vehicle ownership, increasing demand for replacement components, and the need to repair damaged windshields and windows are supporting the expansion of the automotive aftermarket glass market. These factors are creating opportunities for manufacturers, distributors, and replacement service providers, contributing to the overall development of the global auto glass market.
Electric Vehicle Adoption and Advanced Glazing Requirements
The expansion of electric vehicles is creating new opportunities for automotive glass manufacturers. Global electric vehicle sales reached approximately 17 million units in 2024, according to the supplied market report, supported by expanding model availability and growing investment in electrified transportation.
Electric vehicles increasingly incorporate panoramic glass roofs, larger windshields, solar-control coatings, and specialized glazing designed to improve passenger comfort and vehicle efficiency. These features can enhance cabin aesthetics while helping manufacturers optimize aerodynamics and reduce the impact of solar heat.
The supplied report estimates that the incremental glazing value per electric vehicle compared with an equivalent internal combustion engine vehicle can range from USD 150 to USD 400. This creates opportunities for manufacturers to increase average selling prices through premium glazing products.
Automakers are also exploring lightweight glass solutions to reduce vehicle weight and support driving-range objectives. As electric vehicle production expands, demand for advanced glazing technologies is expected to create additional growth opportunities throughout the automotive glass supply chain.
ADAS Integration and Smart Glass Innovation
The increasing integration of advanced driver assistance systems is transforming automotive windshields from conventional safety components into sophisticated technological platforms.
Modern ADAS-equipped vehicles may require windshields compatible with forward-facing cameras, rain and light sensors, heating elements, and heads-up display systems. These applications demand high optical quality, precise manufacturing tolerances, and carefully positioned sensor mounting areas.
Automotive glass manufacturers are developing specialized glazing products that support sensor performance while meeting safety and durability requirements. Precision optical zones and integrated mounting systems can simplify vehicle assembly and help maintain consistent performance.
Smart glass is another important growth area. Electrochromic and other active glazing technologies allow users to adjust transparency or shading in response to electrical signals. These systems are particularly relevant to panoramic roofs and premium electric vehicles.
The combination of ADAS integration, smart glass adoption, and advanced display technologies is encouraging manufacturers to move beyond conventional glazing toward higher-value automotive glass solutions.
Automotive Glass Market Trends to Watch
Three major trends are shaping the global automotive glass industry.
Active smart glass adoption: Electrochromic and other switchable glazing technologies are gaining attention as automakers introduce panoramic roofs and adjustable privacy features. These products offer opportunities to differentiate premium vehicles while improving passenger comfort.
ADAS-compatible windshield development: The expansion of camera-based safety systems is increasing demand for precision-engineered windshields with optical zones, sensor mounting brackets, and integrated heating elements. These developments are strengthening the role of automotive glass in vehicle safety and electronics integration.
Lightweight and energy-efficient glazing: Manufacturers are developing thinner glass, solar-control coatings, and acoustic laminated products to improve vehicle efficiency and cabin comfort. These solutions are particularly relevant to electric vehicles, where energy consumption and driving range remain important considerations.
Additional opportunities are emerging in HUD-integrated windshields, acoustic laminated glass, and advanced solar-control technologies. As vehicles become increasingly connected and electrified, glazing products are expected to perform a wider range of functions beyond basic visibility and protection.
Automotive Glass Market Segmentation
The global automotive glass market is analyzed by glass type, material type, vehicle type, application, end-user, and technology. Each segment reflects different vehicle requirements, manufacturing specifications, and replacement demand.
By Glass Type
The report identifies laminated glass as the leading glass-type segment in 2025. However, a specific market share for this segment is not provided in the supplied data.
Laminated glass is widely used in automotive windshields because its layered construction helps retain glass fragments following an impact. It generally consists of two glass layers bonded with an interlayer, commonly polyvinyl butyral (PVB).
This construction supports occupant safety, reduces the risk of dangerous glass fragmentation, and can contribute to acoustic insulation. Specialized laminated products can also accommodate heads-up displays, solar-control coatings, and ADAS-compatible optical zones.
Tempered glass is commonly used in side and rear windows because of its strength and characteristic breakage pattern. Both laminated and tempered products remain important to automotive manufacturers, with selection depending on the intended application, vehicle design, and applicable safety requirements.
By Material Type
The supplied report identifies IR PVB as the leading material-type segment in 2025, although its exact market share is not disclosed.
PVB interlayers are important in laminated automotive glass because they help bond glass layers, improve impact performance, and support acoustic and optical properties. Specialized interlayer formulations can also contribute to heat management and passenger comfort.
Material innovation is increasingly focused on improving sound insulation, reducing solar heat transmission, supporting advanced displays, and meeting the requirements of modern vehicle platforms.
Manufacturers are also exploring advanced coatings and specialized materials that can improve thermal performance without compromising optical clarity or safety.
By Vehicle Type
The market includes passenger cars and commercial vehicles, among other vehicle categories.
Passenger cars are identified as the leading vehicle-type segment in the supplied report, but a specific share is not provided.
Passenger vehicles require multiple glazing components, including windshields, side windows, rear windows, and increasingly panoramic roofs. Growing demand for electric vehicles and premium vehicle features is encouraging the adoption of advanced glass products in this segment.
Commercial vehicles, including trucks and buses, also represent an important source of demand. These vehicles require durable glazing designed to provide visibility, safety, and long-term performance under demanding operating conditions.
As vehicle fleets expand and manufacturers introduce new models, both passenger and commercial vehicle segments are expected to support automotive glass demand.
By Application
The report identifies windshields as the leading application segment in 2025, although its exact market share is not provided.
Windshields are critical safety components designed to provide visibility, protect occupants, and contribute to vehicle structural performance. Their role is expanding as automakers integrate cameras, sensors, heating elements, and HUD systems into windshield assemblies.
Modern ADAS windshields require precise optical properties and carefully controlled installation positions to support camera accuracy. HUD-compatible windshields also require specialized optical characteristics to display information clearly within the driver's field of view.
Other important applications include side windows, rear windows, sunroofs, and panoramic roofs. Increasing adoption of advanced glazing features is creating opportunities across multiple automotive glass applications.
By End-User
-
Original Equipment Manufacturers (OEMs)
-
Aftermarket
OEMs dominated the automotive glass market in 2025, accounting for approximately 72.5% of total revenues. Their leading position reflects the importance of automotive glass in new vehicle production and the long-term supply agreements between glass manufacturers and automakers.
OEM glass is specified during vehicle development, often several years before production begins. Suppliers must meet strict requirements related to safety, optical quality, dimensional accuracy, durability, and manufacturing consistency.
The growing integration of ADAS, HUD systems, panoramic roofs, and acoustic glazing is further increasing the technical requirements for OEM glass products. Suppliers that can deliver complete glazing solutions and maintain reliable production schedules are well positioned to secure long-term contracts.
The aftermarket accounted for the remaining 27.5% of the market in 2025, according to the supplied segmentation data. This segment includes replacement windshields, side windows, rear windows, and other glazing components damaged through accidents, road debris, weather conditions, and everyday vehicle use.
Aftermarket demand is supported by the large global vehicle fleet and the need to maintain vehicle safety throughout its operating life. However, the increasing complexity of ADAS-equipped windshields is raising the importance of proper installation, sensor calibration, and replacement quality.
By Technology
-
Passive Glass
-
Active Smart Glass
Passive glass dominated the technology segment in 2025, accounting for approximately 63.4% of the market. This category includes conventional laminated and tempered glass, acoustic laminated glazing, and solar-control glass products.
Passive glass remains widely adopted because it offers established safety performance, broad manufacturing availability, and comparatively favorable costs. These characteristics make it suitable for mass-market passenger vehicles and commercial vehicles.
At the same time, active smart glass represents an important growth opportunity. Technologies such as electrochromic glass, suspended particle devices (SPD), and polymer-dispersed liquid crystal (PDLC) systems can provide adjustable transparency, tinting, or privacy features.
These solutions are increasingly relevant to premium vehicles and electric vehicles featuring panoramic roofs. As manufacturing costs decline and automakers seek additional ways to differentiate their products, active smart glass may expand into a wider range of vehicle categories.
Regional Automotive Glass Market Outlook
Asia Pacific
Asia Pacific accounted for 46.9% of the global automotive glass market in 2025, making it the leading regional market. Growth is supported by large-scale vehicle manufacturing, expanding electric vehicle production, technological innovation, and the presence of major automotive glass suppliers.
China represents a particularly important market because of its extensive automotive manufacturing base and rapidly expanding electric vehicle industry. The country's production ecosystem supports demand for windshields, panoramic roofs, laminated glazing, and advanced sensor-compatible glass.
Japan and South Korea contribute through established automotive industries, advanced materials expertise, and precision glass manufacturing capabilities. India is also emerging as an important opportunity as vehicle production, domestic demand, and automotive manufacturing investment expand.
The growing adoption of electric vehicles across the region is encouraging the use of panoramic roofs, solar-control glass, lightweight glazing, and ADAS-compatible windshields. These developments are creating opportunities for manufacturers that can supply advanced products at competitive costs.
Europe
Europe accounted for 21.3% of the global automotive glass market in 2025, according to the supplied report. The region benefits from its established automotive industry, premium vehicle production, stringent safety requirements, and increasing adoption of advanced driver assistance technologies.
Germany, France, the United Kingdom, Italy, and other European markets support demand for high-quality glazing products used in passenger vehicles and commercial vehicles.
The region's emphasis on vehicle safety and advanced electronics is encouraging the adoption of ADAS-compatible windshields and precision optical glass. Electric vehicle development is also creating demand for panoramic roofs, solar-control coatings, acoustic laminated glass, and lightweight glazing.
European automotive glass suppliers are investing in product innovation, manufacturing efficiency, and sustainability to meet evolving vehicle specifications. Demand for replacement glass and sensor recalibration services also supports the aftermarket.
North America
North America accounted for 17.8% of the global automotive glass market in 2025. The region's market is supported by established vehicle manufacturing, a substantial vehicle fleet, demand for replacement glazing, and the growing adoption of advanced vehicle technologies.
The United States represents a major market for automotive glass, with demand generated by passenger vehicles, commercial fleets, and electric vehicles. The increasing use of ADAS systems is raising demand for specialized windshields that accommodate cameras and sensors.
The aftermarket is another important component of the regional market. Windshield damage caused by road debris, weather conditions, and accidents generates replacement demand, while ADAS-equipped vehicles require appropriate sensor recalibration following windshield replacement.
Manufacturers and service providers are investing in advanced glazing products, replacement networks, and calibration capabilities to serve both OEM and aftermarket customers.
Latin America
Latin America accounted for 7.5% of the global automotive glass market in 2025. The region's automotive glass industry is supported by vehicle production, replacement demand, and the expansion of manufacturing operations in markets such as Brazil and Mexico.
Brazil's automotive industry contributes to demand for original equipment glazing and replacement products. Mexico's role in regional vehicle manufacturing also creates opportunities for suppliers serving domestic assembly plants and international automotive supply chains.
The expansion of vehicle fleets, insurance-linked replacement programs, and growing demand for modern vehicle features are supporting market development. However, manufacturers must also manage cost pressures, supply chain requirements, and differences in consumer purchasing power across the region.
Middle East and Africa
The Middle East and Africa accounted for 6.5% of the global automotive glass market in 2025, according to the supplied regional breakdown.
Demand is supported by vehicle fleet expansion, automotive imports, commercial transportation, and replacement requirements. Saudi Arabia and the United Arab Emirates offer opportunities associated with vehicle ownership, premium vehicles, and investment in transportation infrastructure.
South Africa contributes through its automotive manufacturing industry and regional vehicle supply networks. Across the region, windshield replacement, vehicle maintenance, and the growing availability of modern vehicles support demand for automotive glazing.
As vehicle fleets expand and advanced safety features become more common, demand for high-quality replacement glass and specialized installation services may create additional opportunities.
Competitive Landscape
Automotive glass manufacturers compete through product innovation, manufacturing efficiency, long-term OEM relationships, geographic expansion, and the development of advanced glazing technologies.
Leading companies are investing in ADAS-compatible windshields, HUD-integrated glass, acoustic laminated products, solar-control coatings, and smart glass solutions. These products enable manufacturers to move beyond conventional glazing and supply higher-value components for modern vehicles.
The competitive landscape is influenced by the capital-intensive nature of float glass manufacturing, strict automotive quality requirements, and the long development cycles associated with vehicle platforms. Established suppliers benefit from manufacturing scale, technical expertise, and relationships with major automakers.
Major companies operating in the global automotive glass market include:
-
AGC Inc.
-
Compagnie de Saint-Gobain
-
Fuyao Glass Industry Group Co., Ltd.
-
NSG Group (Pilkington)
-
Xinyi Glass Holdings Limited
-
Guardian Industries
-
Corning Incorporated
-
Gentex Corporation
-
Safelite Group
-
Webasto Group
Key Company Developments
AGC Inc.
AGC is a major automotive glass manufacturer supplying windshields, laminated glazing, solar-control glass, and advanced glazing systems to global automakers. Its product portfolio includes ADAS-compatible windshield modules, HUD-compatible glass, acoustic laminated products, and smart glazing solutions.
In March 2024, AGC Automotive Europe introduced a vehicle-integrated photovoltaic panoramic sunroof concept incorporating solar cells. The development reflects growing interest in glazing technologies that can contribute to vehicle energy efficiency and functional integration.
Fuyao Glass Industry Group Co., Ltd.
Fuyao Glass is a major automotive glazing supplier headquartered in China, serving international automakers with laminated windshields, tempered glass, acoustic glazing, solar-control products, and panoramic roof glass.
In December 2023, Fuyao Glass announced an investment of CNY 3.3 Billion in a new automotive glass plant in Fuqing, Fujian. The proposed facility was designed to provide annual capacity exceeding 20.5 million square meters, supporting demand associated with new energy vehicles and automotive manufacturing.
Compagnie de Saint-Gobain
Saint-Gobain's Sekurit division supplies automotive glazing, including acoustic laminated windshields, panoramic roofs, solar-control glass, and ADAS-compatible products.
In February 2026, Saint-Gobain Sekurit joined ZEISS, tesa, and Hyundai Mobis in forming the QuadAlliance, a cross-industry collaboration intended to accelerate the development and production of holographic windshield display technology.
The initiative highlights the growing convergence of automotive glass, optical technologies, and in-vehicle display systems.
NSG Group (Pilkington)
NSG Group, operating under the Pilkington brand, is a global automotive glass supplier serving major automakers. Its product portfolio includes laminated windshields, solar-control glass, acoustic glazing, and products designed to support advanced driver assistance systems.
At Auto Glass Week 2024, Pilkington North America showcased an upgraded calibration package intended to support ADAS camera calibration in automotive glass replacement applications.
Xinyi Glass Holdings Limited
Xinyi Glass is an important glass manufacturer with a growing presence in automotive glazing. The company competes through manufacturing scale, competitive pricing, capacity expansion, and supply to vehicle manufacturers.
Its position in the market reflects the increasing role of Chinese glass manufacturers in global automotive supply chains.
Where Are the Biggest Automotive Glass Market Opportunities?
The automotive glass industry presents opportunities across several technology, manufacturing, and aftermarket applications.
-
Active smart glass: Electrochromic and switchable privacy glass can create higher-value opportunities in panoramic roofs and premium electric vehicles.
-
ADAS-compatible windshields: Growing integration of cameras and sensors is increasing demand for precision-engineered glazing that supports advanced safety systems.
-
HUD-integrated glass: Heads-up displays require specialized optical glass, creating opportunities for suppliers offering high-precision laminated windshields.
-
Lightweight and solar-control glazing: Advanced coatings and thinner glass can help reduce vehicle weight, manage cabin heat, and support electric vehicle efficiency.
-
Acoustic laminated glass: Specialized interlayers can reduce road and wind noise, particularly benefiting electric vehicles with quieter powertrains.
-
Emerging-market aftermarket expansion: Large vehicle fleets in India, Brazil, and Southeast Asia create opportunities for replacement glass, distribution, and installation services.
-
OEM partnerships: Long-term supply agreements with vehicle manufacturers can support predictable demand and encourage investment in specialized production capabilities.
-
Advanced calibration services: The integration of ADAS systems is creating demand for professional windshield replacement and sensor recalibration services.
These opportunities are becoming increasingly important as automotive glazing evolves into a multifunctional vehicle component. Manufacturers that combine optical precision, safety, lightweight design, and electronic integration can strengthen their competitive position.
Get Detailed Automotive Glass Market Intelligence
The headline market figures provide a useful overview of the industry's direction, but businesses evaluating market entry, manufacturing investments, product development, competitive positioning, or regional expansion may require more detailed market intelligence.
A comprehensive automotive glass market report can provide insights into:
-
Market size and growth forecasts
-
Glass-type analysis
-
Material-type segmentation
-
Vehicle-type assessment
-
Application-wise market breakdown
-
OEM and aftermarket demand
-
Passive and active smart glass technologies
-
Regional and country-level market performance
-
Competitive landscape and key company profiles
-
Supply chain and value chain analysis
-
Emerging technological developments
-
Investment opportunities and industry challenges
These insights can help manufacturers, suppliers, investors, and automotive industry stakeholders evaluate demand patterns and identify opportunities across the global automotive glass value chain.
Request a Sample Report: https://www.imarcgroup.com/automotive-glass-market/requestsample
Automotive Glass Market FAQs
What is the current size of the global automotive glass market?
The global automotive glass market reached USD 20.0 Billion in 2025 and is estimated to reach USD 21.4 Billion in 2026. It is projected to reach USD 31.7 Billion by 2034.
What is the CAGR of the automotive glass market?
The global automotive glass market is projected to expand at a CAGR of 5.02% during 2026–2034.
Which region leads the automotive glass market?
Asia Pacific is the leading regional market, accounting for 46.9% of global revenue in 2025. Its position is supported by large-scale automotive manufacturing and the presence of major vehicle and glass manufacturers in China, Japan, South Korea, and India.
Which end-user segment dominates the automotive glass market?
OEMs accounted for approximately 72.5% of the market in 2025, reflecting the importance of factory-fitted glazing in new vehicle production and long-term supply agreements between automakers and glass manufacturers.
Which technology segment dominates the automotive glass market?
Passive glass held approximately 63.4% of the market in 2025. It remains widely used because of its established safety performance, manufacturing availability, and cost advantages. Active smart glass is an important growth opportunity as automakers introduce adjustable glazing and panoramic roof technologies.
What are the major trends in the automotive glass market?
Key trends include smart glass adoption, ADAS-compatible windshields, HUD-integrated glazing, lightweight solar-control glass, acoustic laminated products, and increasing demand for aftermarket replacement and calibration services.
Who are the major companies in the automotive glass market?
Major companies include AGC Inc., Saint-Gobain Sekurit, Fuyao Glass Industry Group, NSG Group (Pilkington), Xinyi Glass, Guardian Industries, Corning, Gentex, Safelite Group, and Webasto Group.
Conclusion
The global automotive glass market is evolving as vehicle manufacturers increasingly prioritize safety, energy efficiency, advanced driver assistance systems, and technology-enabled glazing. Valued at USD 20.0 Billion in 2025, the market is projected to reach USD 31.7 Billion by 2034, expanding at a CAGR of 5.02% during 2026–2034.
Growth opportunities are emerging across ADAS-compatible windshields, active smart glass, panoramic roofs, HUD-integrated glazing, lightweight solar-control products, and aftermarket replacement services. Asia Pacific remains the leading regional market, while OEMs continue to account for the largest share of end-user demand.
Companies that invest in advanced materials, manufacturing precision, smart glazing technologies, and strong relationships with automakers can strengthen their competitive positioning in the evolving automotive glass industry.
About the Author
IMARC Group is a global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers market intelligence across sectors including automotive, energy and mining, construction and manufacturing, chemicals and materials, and more.
Media & Sales Contact
IMARC Group
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104

 English
 Arabic
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek
 Bengali