


Erythropoietin Drugs Market 2026: Size, Share, Industry Trends, Growth and Forecast to 2034
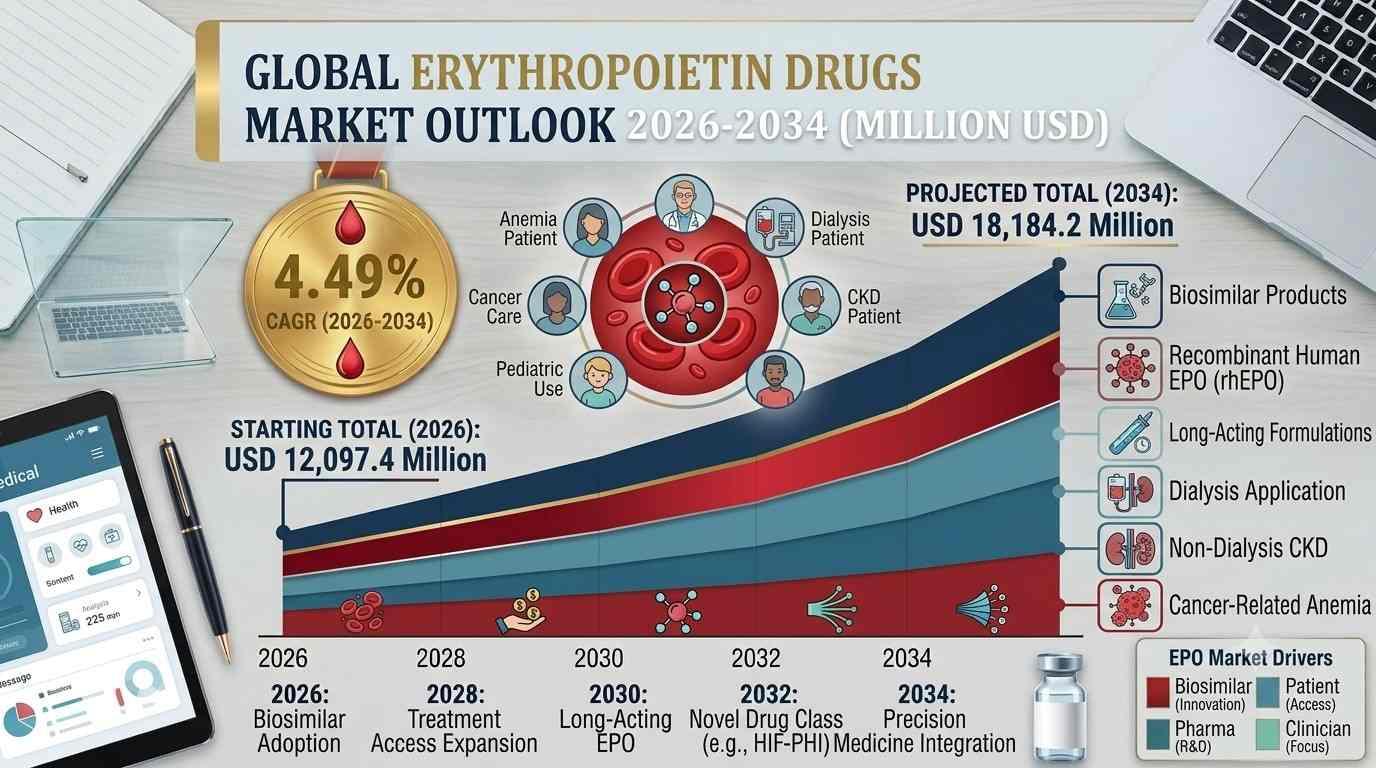
According to IMARC Group, the global erythropoietin drugs market size reached USD 12,097.4 Million in 2025 and is projected to reach USD 18,184.2 Million by 2034, expanding at a CAGR of 4.49% during 2026-2034. This steady growth trajectory reflects the rising global burden of chronic kidney disease and cancer, continuous innovation in biopharmaceutical research, and the accelerating shift toward cost-effective biosimilar formulations across both developed and emerging healthcare systems.
Erythropoietin Drugs Industry Overview
Erythropoietin drugs are biologic or biosimilar formulations designed to stimulate red blood cell production in patients whose bodies are unable to generate sufficient natural erythropoietin. They are most widely used to manage anemia associated with chronic kidney disease, chemotherapy-induced anemia in cancer patients, and anemia linked to certain HIV treatment regimens. By reducing reliance on repeated blood transfusions, these therapies help lower treatment-related risks while supporting better long-term patient outcomes.
Erythropoietin therapies are deployed across a broad continuum of clinical settings:
- Nephrology: Managing anemia associated with chronic kidney disease, particularly in dialysis-dependent patients
- Oncology: Supporting patients experiencing chemotherapy-induced anemia across a range of cancer types
- Hematology: Addressing broader red-blood-cell disorders that require erythropoiesis support
- HIV care: Managing anemia linked to certain antiretroviral treatment regimens
- Homecare and specialty clinics: Extending EPO therapy access beyond traditional hospital settings
Global Erythropoietin Drugs Market Size & Key Statistics
Below are the key Erythropoietin Drugs Market statistics drawn from IMARC Group's comprehensive market analysis:
Base Year - 2025
Historical Period - 2020-2025
Forecast Period - 2026-2034
Erythropoietin Drugs Market Size in 2025 - USD 12,097.4 Million
Market Forecast in 2034 - USD 18,184.2 Million
Market Growth Rate (2026-2034) - 4.49% CAGR
Largest Region - North America (40.5% share in 2025)
Leading Drug Class - Biologics
Leading Product Type - Epoetin-alfa
Leading Application - Kidney Disorder
Leading End User - Hospitals
Request for a Sample Report for Detailed Erythropoietin Drugs Market Share Evaluation: https://www.imarcgroup.com/erythropoietin-drugs-market/requestsample
Key Market Drivers & Erythropoietin Drugs Market Trends in 2026
Several powerful forces are shaping Erythropoietin Drugs Market Trends and fuelling sustained growth expectations across global anemia-care markets:
1. Rising Global Burden of Chronic Kidney Disease and Cancer
The growing incidence of chronic kidney disease and cancer worldwide is a primary driver of erythropoietin drug demand, since both conditions frequently cause anemia that requires erythropoiesis-stimulating therapy. Cancer incidence continues to climb globally, particularly among aging populations, intensifying the need for supportive care such as EPO therapy to manage chemotherapy-induced anemia. At the same time, the expanding population of patients with chronic kidney disease, especially those on dialysis, is sustaining consistent demand for erythropoietin-based anemia management.
2. Continued Advances in Biopharmaceutical Research
Ongoing innovation in biopharmaceutical research is enabling the development of next-generation erythropoietin formulations that improve efficacy and convenience. Long-acting formulations that reduce dosing frequency are helping improve patient compliance, while biotechnology firms continue to refine erythropoiesis-stimulating agents aimed at improving safety profiles and minimizing side effects. These advances are expanding the range of therapeutic options available to prescribers and patients alike.
3. Accelerating Adoption of Biosimilars
Mounting cost pressures across global healthcare systems, combined with patent expirations of reference biologics, are driving a marked increase in the use of erythropoietin biosimilars. These lower-cost alternatives offer comparable efficacy and safety to originator products, making them increasingly attractive in both developed and emerging markets. Governments and healthcare systems are actively encouraging biosimilar adoption to control treatment costs, a trend that is broadening patient access and expanding overall erythropoietin drugs market share for biosimilar manufacturers.
4. Growing Application in Personalized Anemia Management
Healthcare providers are increasingly tailoring erythropoietin dosing regimens to individual patient profiles, supported by closer monitoring of hemoglobin response and side-effect risk. This personalized approach is helping optimize therapeutic outcomes across dialysis, oncology, and HIV-related anemia care, while regulatory bodies continue to streamline approval pathways for new indications and biosimilar entrants.
Key Market Segmentation
By Drug Class
- Biologics
- Biosimilars
Biologics represent the largest drug class segment, accounting for 55.2% of the market in 2025. Originator biologic erythropoietin products continue to benefit from deep clinical validation, established prescriber trust, and broad usage across nephrology and oncology settings, even as biosimilar competition intensifies.
By Product Type
- Epoetin-alfa
- Epoetin-beta
- Darbepoetin-alfa
- Others
Epoetin-alfa leads the product-type segment, holding 35.6% of the market in 2025. It remains a critical erythropoiesis-stimulating agent for managing anemia related to chemotherapy, chronic kidney disease, and certain HIV treatments, with manufacturers continuing to refine formulations for improved bioavailability and more flexible dosing.
By Application
- Hematology
- Kidney Disorder
- Cancer
- Others
Kidney disorder is the leading application segment in 2025, as EPO drugs play a vital role in managing anemia among chronic kidney disease patients, particularly those undergoing dialysis. Nephrology clinics are increasingly integrating erythropoietin therapy into routine care protocols to maintain target hemoglobin levels and reduce transfusion dependence.
By End User
- Hospitals
- Homecare
- Specialty Clinics
- Others
Hospitals account for the largest end-user share in 2025, as nephrology and oncology departments increasingly integrate EPO therapies into treatment protocols for dialysis and chemotherapy patients. The growing availability of biosimilars is helping hospitals reduce treatment costs while maintaining therapeutic efficacy.
Regional Erythropoietin Drugs Market Analysis
North America - Largest (40.5% share)
United States & Canada; advanced dialysis and oncology infrastructure, high chronic kidney disease and cancer prevalence, strong biosimilar adoption, leading pharmaceutical manufacturers headquartered here
Europe: Germany, France, UK, Italy, Spain, Russia; supportive EMA regulatory frameworks, rising biosimilar uptake, growing demand for personalized anemia therapies
Asia Pacific: China, Japan, India, South Korea, Australia, Indonesia; rapid healthcare infrastructure expansion, rising chronic disease burden, expanding health insurance coverage
Latin America: Brazil, Mexico; growing government-subsidized healthcare access, increasing clinical trial activity and regulatory harmonization
Middle East & Africa: Rising chronic kidney disease prevalence, national health transformation programmes such as Saudi Vision 2030, growing medical tourism
North America leads the global erythropoietin drugs market share, underpinned by the United States' advanced dialysis and oncology care infrastructure, high chronic disease prevalence, and continued expansion of biosimilar adoption to manage treatment costs. Within the region, the United States alone accounts for 88.20% of the North American market, driven in large part by chronic kidney disease affecting an estimated 14% of the U.S. population.
Asia Pacific represents one of the fastest-growing regional markets, supported by rising chronic disease burden, expanding healthcare infrastructure, and growing government initiatives to broaden access to advanced biologics and biosimilars across the region.
Connect for Detailed Erythropoietin Drugs Market Analysis - Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=4270&flag=C
Leading Players in the Global Erythropoietin Drugs Industry
The global erythropoietin drugs market features a mix of established biologics manufacturers and growing biosimilar specialists. Key companies covered in the IMARC Group report include:
- Amgen Inc.
- Biocon Limited
- Dr. Reddy's Laboratories Ltd.
- F. Hoffmann-La Roche AG
- Intas Pharmaceuticals Ltd.
- Johnson & Johnson
- LG Chem Ltd.
- Pfizer Inc.
- Sun Pharmaceutical Industries Limited
- Teva Pharmaceutical Industries Ltd.
Market participants are investing heavily in long-acting formulations, biosimilar development, and strategic partnerships with biotechnology firms to expand their product portfolios and distribution networks, while pursuing regulatory approvals for new indications and formulations.
About Us
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multi-disciplinary team of industry experts, IMARC delivers thorough, reliable market intelligence across sectors including Healthcare, Technology, Chemicals, Energy, Food & Beverages, and more.
Contact Us
IMARC Group
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek
 Bengali