


Saudi Arabia Orthopedic Implants Market Report by Type, Product and Biomaterial, 2026-2034
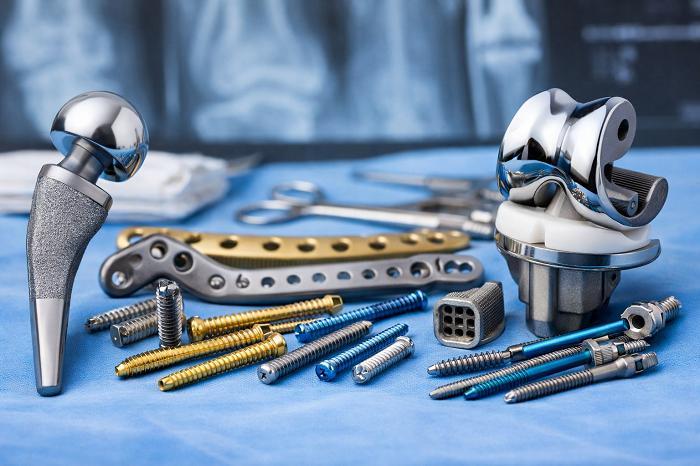
The Saudi Arabia orthopedic implants market driven by demographic shifts, increasing orthopedic conditions, technological advancements, rising adoption of minimally invasive procedures, expanding healthcare infrastructure, and growing collaboration between healthcare institutions and implant manufacturers. Saudi Arabia orthopedic implants market size reached USD 539.5 Million in 2025. Looking forward, IMARC Group expects the market to reach USD 751.6 Million by 2034, exhibiting a growth rate (CAGR) of 3.75% during 2026-2034.
The market is witnessing strong growth momentum as Saudi Arabia's healthcare system continues to expand its capacity for advanced orthopedic procedures. Growing demand for knee and hip replacements, spinal implants, trauma devices, dental implants, and orthobiologics is encouraging manufacturers and healthcare providers to invest in advanced implant technologies. The country's medical equipment market is estimated at approximately USD 2 Billion, while government policies are increasingly encouraging local production of high-value medical products, including orthopedic devices, prostheses, and implants.
How AI is Reshaping the Future of Saudi Arabia Orthopedic Implants Market?
AI is increasingly influencing orthopedic implant development, surgical planning, manufacturing, and patient-specific treatment approaches. AI-powered technologies can analyze medical imaging, support implant selection, improve surgical planning, and enable manufacturers to develop more personalized orthopedic solutions.
- AI-Powered Personalized Implant Design: AI-enabled imaging and modeling systems can analyze patient anatomy and help create customized implant designs. This is particularly relevant for complex joint reconstruction and bone replacement procedures where anatomical fit is critical.
- AI-Assisted Surgical Planning and Robotic Procedures: AI-supported surgical platforms can combine medical imaging with computer-assisted planning to improve the precision of orthopedic procedures. Advanced robotic technology is already being adopted by Saudi healthcare providers, including robotic knee replacement procedures performed in Riyadh.
- Predictive Analytics for Implant Performance: AI can analyze clinical and operational data to identify patterns related to implant performance, patient recovery, revision procedures, and complications. Manufacturers and healthcare providers can use these insights to improve implant design and treatment protocols.
- AI-Enabled 3D Printing and Custom Implants: AI combined with additive manufacturing can support the development of patient-specific implants with optimized geometry and material distribution. NUPCO has identified an investment opportunity for local production of personalized orthopedic implants using 3D printing, with indicative annual addressable demand of SAR 120 Million.
Grab a sample PDF of this report:
https://www.imarcgroup.com/saudi-arabia-orthopedic-implants-market/requestsample
Market Growth Factors
The Saudi Arabia orthopedic implants market is driven by the increasing prevalence of musculoskeletal disorders, demographic changes, expanding healthcare infrastructure, and rising demand for advanced surgical interventions. The country's population is experiencing a significant demographic shift, with the population aged 60 and above projected by UNFPA to increase from approximately 2 Million to 10.5 Million, representing 23.7% of the population. This demographic transition is expected to increase demand for treatments addressing age-related joint degeneration, arthritis, fractures, and spinal disorders.
Technological innovation is another major market driver. Manufacturers are increasingly developing implants using advanced biomaterials, 3D printing, computer-assisted design, and minimally invasive surgical technologies. These developments allow orthopedic specialists to address complex conditions while improving implant fit, surgical precision, and patient recovery. Saudi Arabia's healthcare transformation strategy is also encouraging investments in advanced medical technologies and specialized healthcare facilities.
Government investment in healthcare infrastructure is creating additional opportunities for orthopedic implant manufacturers and suppliers. Saudi Arabia has announced USD 13.8 Billion in planned investment in medical facilities, while healthcare remains a major focus of Vision 2030. The government is also seeking to increase private-sector participation in healthcare and expand access to advanced medical services.
Localization is becoming an important trend across the orthopedic implant supply chain. Saudi authorities are encouraging domestic manufacturing and technology transfer for high-value medical products. The Local Content and Government Procurement Authority has supported localization initiatives covering orthopedic implants for accidents and fractures, including devices designed to treat bone fractures and deformities.
The National Unified Procurement Company, or NUPCO, is also identifying opportunities for private-sector participation in medical-device manufacturing. One identified opportunity involves establishing local production of personalized orthopedic implants using 3D printing and Saudi Arabia's petrochemical and metals resources. The opportunity has an indicative annual addressable demand of SAR 120 Million, highlighting the commercial potential of localized implant manufacturing.
Saudi Arabia's regulatory infrastructure is simultaneously supporting quality and safety standards for orthopedic implants. The Saudi Food and Drug Authority maintains standards covering surgical implants, including specific requirements for hip and knee joint replacement implants and testing requirements for orthopedic prostheses.
Market Segmentation
Type Insights:
- Knee
- Hip
- Wrist and Shoulder
- Dental
- Spine
- Ankle
- Others
Knee and hip applications represent important areas within the orthopedic implants market as healthcare providers address joint degeneration, arthritis, fractures, and mobility-related conditions. Growing adoption of advanced joint replacement procedures, coupled with robotic and minimally invasive surgical technologies, is supporting demand for technologically advanced implants.
Product Insights:
- Reconstructive Joint Replacements
- Knee Replacement Implants
- Hip Replacement Implants
- Extremities
- Spinal Implant
- Spinal Fusion Implant
- Vertebral Compression Fracture Devices
- Motion Preservation Devices/Non-Fusion Devices
- Dental Implants
- Root Form Dental Implants
- Plate Form Dental Implants
- Trauma
- Orthobiologics
- Demineralized Bone Matrix
- Allograft
- Bone Morphogenetic Protein
- Viscosupplementation Products
- Synthetic Bone Substitutes
- Others
- Others
Reconstructive joint replacements represent a major product category as demand increases for knee, hip, and extremity implants. Spinal implants and trauma products are also benefiting from the growing need for specialized surgical solutions, while orthobiologics are supporting regenerative approaches to musculoskeletal treatment.
Biomaterial Insights:
- Metallic Biomaterials
- Stainless Steel
- Titanium Alloy
- Cobalt Alloy
- Others
- Ceramic Biomaterials
- Polymeric Biomaterials
- Others
Metallic biomaterials remain widely used because of their strength, durability, and established applications in orthopedic procedures. Titanium alloys, stainless steel, and cobalt alloys are used across joint replacement, trauma, and spinal applications. At the same time, ceramic and polymeric biomaterials are gaining attention as manufacturers focus on biocompatibility, wear resistance, lightweight designs, and improved implant performance.
End User Insights:
- Hospitals
- Orthopedic Clinics
- Ambulatory Surgical Centers
- Others
Hospitals represent a major end-user segment because they provide comprehensive orthopedic surgery capabilities and handle complex joint replacement, spinal, trauma, and reconstructive procedures. Orthopedic clinics and ambulatory surgical centers are also gaining importance as healthcare delivery becomes increasingly specialized and procedure-focused. Expanding healthcare infrastructure and private-sector participation are creating additional opportunities across these facilities.
Regional Insights:
- Northern and Central Region
- Western Region
- Eastern Region
- Southern Region
The Northern and Central Region represents an important market due to the concentration of major healthcare facilities, specialized hospitals, medical technology companies, and healthcare investment activity around Riyadh and surrounding areas. The Western Region also plays a significant role because of its large population base and healthcare infrastructure in cities such as Jeddah and Makkah. The Eastern and Southern regions are contributing to market expansion as healthcare facilities and specialized medical services continue to develop.
Recent Development & News
- October 2025: The Local Content and Government Procurement Authority announced agreements to localize the manufacturing and knowledge transfer of several medical and pharmaceutical products. The initiatives included localization of orthopedic implants used for accidents and fractures, including devices for treating bone fractures and deformities.
- November 2025: Saudi Arabia's Ministry of Health inaugurated the SHIFT Innovation Center in Riyadh in collaboration with Siemens Healthineers. The center focuses on healthcare innovation, research, strategic partnerships, knowledge transfer, and localization of technologies to address healthcare needs in Saudi Arabia and the wider region.
- December 2025: Dallah Al Nakheel Hospital in Riyadh announced the successful performance of a knee replacement procedure using advanced robotic surgical technology on a patient with advanced osteoarthritis and severe knee joint erosion, highlighting the increasing adoption of advanced orthopedic surgical capabilities in Saudi Arabia.
- May 2026: The U.S. Department of Commerce highlighted Saudi Arabia's healthcare sector as a major investment opportunity, noting that healthcare accounts for approximately 60% of GCC healthcare expenditure and that the country is prioritizing medical-device localization, private-sector participation, and advanced healthcare infrastructure.
If you require any specific information that is not covered currently within the scope of the report, we will provide the same as a part of the customization.
About Us
IMARC Group is a global management consulting firm that helps the world's most ambitious changemakers to create a lasting impact. The company provides a comprehensive suite of market entry and expansion services. IMARC offerings include thorough market assessment, feasibility studies, company incorporation assistance, factory setup support, regulatory approvals and licensing navigation, branding, marketing and sales strategies, competitive landscape and benchmarking analyses, pricing and cost research, and procurement research.
Contact Us
IMARC Group
134 N 4th St. Brooklyn, NY 11249, USA
Email: sales@imarcgroup.com
Tel No: (D) +91 120 433 0800
United States: +1-201-971-6302

 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek
 Bengali