


Business Jet Market Poised to Reach USD 28.54 Billion by 2034 as On-Demand Aviation Gains Traction
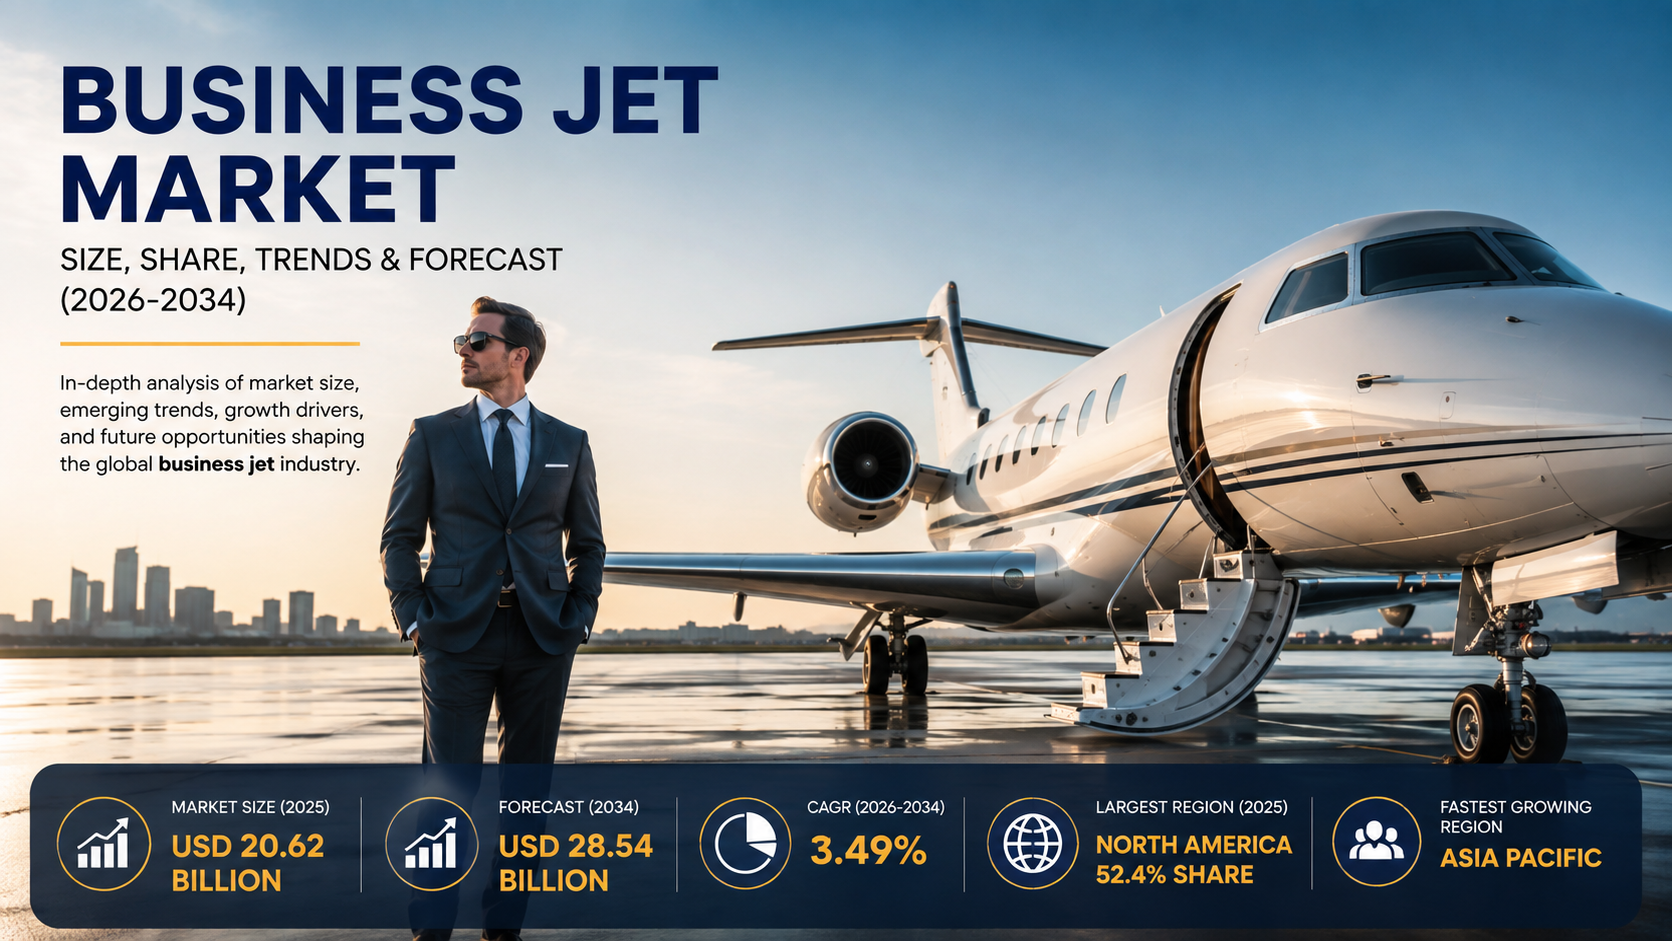
The global business jet market reached USD 20.62 Billion in 2025. Looking forward, the market is projected to reach USD 28.54 Billion by 2034, exhibiting a growth rate (CAGR) of 3.49% during 2026-2034. Rising inclination toward business jets among corporate executives and high-net-worth individuals, growing traction of fractional ownership and jet-sharing models, increasing demand for specialized medical transportation, expansion of private aviation infrastructure, and technological advancements in sustainable aviation are some of the key factors driving market growth.
Business Jet Market Key At a Glance
-
Base Year: 2025
-
Historical Period: 2020–2025
-
Forecast Period: 2026–2034
-
Market Size (2025): USD 20.62 Billion
-
Market Forecast (2034): USD 28.54 Billion
-
CAGR (2026–2034): 3.49%
-
Leading Region: North America
-
North America Market Share (2025): 52.4%
-
Fastest-Growing Region: Asia Pacific
-
Leading Business Model: On-Demand Service – 58.4%
-
Leading Point of Sale: OEM – 62.4%
Request for a Sample Report for Detailed Evaluation: https://www.imarcgroup.com/business-jet-market/requestsample
Business Jet Market Report: Key Highlights
-
Market Size & Growth: The global business jet market reached USD 20.62 Billion in 2025 and is projected to reach USD 28.54 Billion by 2034, registering a CAGR of 3.49% during 2026–2034.
-
Regional Leadership: North America dominates the market with a 52.4% revenue share in 2025, supported by extensive private aviation infrastructure, a high concentration of corporate headquarters, and an established business aviation culture.
-
Fastest-Growing Region: Asia Pacific represents the fastest-growing regional market, driven by rising ultra-high-net-worth individual (UHNWI) populations, expanding private aviation infrastructure, and increasing corporate activity across China, India, and Southeast Asia.
-
Leading Business Model: On-demand service accounts for 58.4% of the market in 2025, reflecting increasing preference for flexible charter services and jet-card programs that provide access without the capital requirements associated with aircraft ownership.
-
Leading Point of Sale: OEM sales hold a 62.4% share, supported by demand for new-generation aircraft featuring advanced avionics, composite airframes, extended range, and enhanced cabin specifications.
-
Key Market Drivers: Rising corporate demand for time-efficient travel, growth of fractional ownership and jet-card programs, expansion of private aviation infrastructure, and increasing medical and VVIP transportation requirements are supporting market growth.
-
Key Market Trends: Increasing adoption of on-demand charter services, sustainable aviation fuel (SAF), long-range ultra-wide-cabin jets, advanced avionics, high-speed connectivity, predictive maintenance, and digital booking platforms are shaping the market.
-
Key Challenges: High aircraft acquisition and operating costs, stringent emission regulations, geopolitical risks, airspace restrictions, disposal challenges, and regulatory complexity across jurisdictions may constrain market expansion.
-
Emerging Opportunities: SAF integration, hybrid-electric propulsion, digital charter platforms, emerging market expansion, and advanced predictive maintenance technologies are creating new opportunities.
What Is Driving Business Jet Market Growth in 2026?
Rising Corporate Demand for Time-Efficient Travel
The growing requirement for time-efficient corporate mobility represents one of the major factors supporting business jet market growth. Business jets enable executives and corporate travelers to travel directly between city pairs while avoiding commercial airline layovers and accessing secondary airports that may not be served by scheduled carriers.
Business aviation also provides passengers with secure and productive cabin environments, allowing confidential business discussions and continued work during travel. The strong integration of private aviation into corporate operations, particularly in North America, is further supporting market expansion.
As businesses increasingly prioritize executive productivity and flexible travel schedules, demand for business jets is expected to continue increasing across corporate and institutional users.
Growth of Fractional Ownership and Jet-Card Programs
The increasing adoption of fractional ownership and jet-card programs is broadening access to business aviation. These models allow corporations and individuals to use private aircraft without assuming the full capital and operational obligations associated with outright ownership.
Fractional ownership enables customers to purchase a share of an aircraft with guaranteed availability and professional aircraft management, while jet-card programs provide prepaid flight hours at predetermined rates. Digital charter platforms are also making business aviation more accessible by enabling users to arrange flights according to their individual schedules and aircraft requirements.
This shift toward flexible, utilization-based aviation models is supporting the expansion of the business jet customer base beyond traditional ultra-high-net-worth individuals and large corporations.
Expansion of Private Aviation Infrastructure
The expansion of private aviation infrastructure is another major factor driving the market. Governments and aviation authorities across regions including the Gulf Cooperation Council (GCC), Southeast Asia, and India are investing in dedicated business aviation terminals, private hangars, customs facilities, and other infrastructure.
The development of fixed-base operator (FBO) networks is improving accessibility and operational efficiency for private aircraft users. Increasing infrastructure availability across secondary cities is also creating new opportunities for business jet operators and charter companies.
As private aviation infrastructure continues to develop, business jet connectivity is expected to expand across emerging aviation markets.
Medical and VVIP Transportation Requirements
Growing institutional demand for medical airlift, organ transportation, and government and VVIP travel is creating a stable demand segment for specialized business jets. These aircraft can be configured with dedicated medical equipment, specialized cabin layouts, and other features required for urgent transportation.
The ability to provide rapid-response transportation while reaching airports closer to final destinations makes business jets particularly suitable for time-sensitive medical and government applications.
Business Jet Market Trends
Surge in On-Demand Charter and Digital Booking Platforms
The business aviation industry is experiencing increasing adoption of on-demand charter services and digital booking platforms. The post-pandemic period accelerated demand for private aviation as some travelers shifted away from commercial first-class travel toward private aircraft.
Digital platforms are supporting this trend by simplifying aircraft discovery, booking, and payment processes. Dynamic charter pricing and jet-card programs are further expanding access to business aviation.
The trend is particularly relevant across Europe and Asia Pacific, where changing corporate travel patterns and developing private aviation infrastructure are creating new demand opportunities.
Rise of Sustainable Aviation Fuel Adoption
Sustainable aviation fuel (SAF) is becoming increasingly important to the business jet industry as manufacturers and operators respond to tightening emissions standards and corporate sustainability commitments.
Business jet manufacturers are investing in SAF-compatible aircraft and propulsion technologies, while governments and aviation authorities are developing blending mandates and sustainability frameworks. Gulfstream Aerospace's transatlantic flight powered entirely by SAF in 2023 represented an important industry milestone.
Increasing SAF availability and regulatory support are expected to influence future fleet replacement and aircraft development strategies.
Increased Demand for Long-Range Ultra-Wide-Cabin Jets
Demand for long-range and ultra-wide-cabin business jets is increasing as corporate travelers increasingly prioritize nonstop journeys that maximize productivity and reduce airport exposure.
Aircraft categories represented by platforms such as the Gulfstream G700/G800 and Bombardier Global 7500/8000 are benefiting from this shift. Extended range, spacious cabins, advanced connectivity, and enhanced passenger comfort are becoming increasingly important purchasing considerations.
The trend toward fewer but longer nonstop journeys is expected to support demand for large-cabin, ultra-long-range business jets through the forecast period.
Integration of Advanced Avionics and Connectivity Systems
Business jet manufacturers are increasingly integrating advanced avionics and connectivity systems to improve flight safety, operational efficiency, and passenger experience.
Next-generation aircraft feature technologies such as synthetic vision displays, head-up displays (HUDs), automatic terrain awareness systems, touchscreen flight decks, and high-speed satellite connectivity. Passenger expectations have also evolved from basic internet access toward high-speed connectivity capable of supporting enterprise applications, video conferencing, and immersive entertainment.
As connectivity becomes a standard component of premium business aviation, manufacturers are increasingly differentiating aircraft through advanced digital and cabin technologies.
Growing Adoption of Predictive Maintenance and Digital Twin Technology
Predictive maintenance and digital twin technologies are becoming increasingly relevant to business jet operators seeking to reduce unscheduled maintenance and improve fleet utilization.
OEM health-monitoring platforms can analyze engine telemetry, structural sensor information, and avionics diagnostics to identify potential component failures before they occur. Systems such as Bombardier's Smart Link Plus and Honeywell's GoDirect Flight demonstrate the growing role of connected maintenance technologies.
The continued development of artificial intelligence and real-time aircraft monitoring is expected to support improved maintenance planning and lifecycle cost management.
Business Jet Market Segmentation Analysis
The market has been segmented based on type, business model, range, point of sale, and region.
By Business Model
-
On-Demand Service
-
Ownership
On-Demand Service
The on-demand service segment dominates the business model category, accounting for 58.4% of the market in 2025. The segment includes flexible charter services, air taxis, branded charter offerings, and jet-card programs.
These models provide corporate and individual customers with access to private aviation without requiring the substantial capital investment and operational responsibilities associated with aircraft ownership. Flexible scheduling, access to different aircraft categories, and the elimination of maintenance and crew-management obligations are supporting segment growth.
Ownership
Ownership accounted for the remaining 41.6% in 2025 and includes fractional and full outright ownership. Fractional ownership allows corporations and other users to purchase shares in aircraft while receiving guaranteed availability and professional management services.
Full ownership remains particularly relevant among ultra-high-net-worth individuals and government entities seeking dedicated aircraft with customized interiors, equipment, and operating arrangements.
By Point of Sale
-
OEM
-
Aftermarket
OEM
OEM represents the largest point-of-sale segment, accounting for 62.4% of the market in 2025. Demand for new-generation aircraft is being supported by advanced avionics, composite airframes, modern engine platforms, improved range, and enhanced cabin specifications.
Purchasing directly from manufacturers also provides customers with aircraft customization, manufacturer warranties, and access to proprietary maintenance and lifecycle-support programs.
Aftermarket
The aftermarket segment accounts for 37.6% and encompasses pre-owned aircraft transactions, MRO services, avionics upgrades, cabin refurbishment, and component supply.
The long operational life of business jets, typically spanning 20–30 years, creates sustained demand for maintenance, regulatory compliance upgrades, cabin refurbishment, and replacement components.
By Type
The market covers multiple business jet categories, ranging from entry-level light jets designed for short-range regional travel to midsize aircraft and large ultra-long-range platforms capable of nonstop intercontinental travel.
Large business jets represent the leading type segment, supported by increasing demand for extended range, spacious cabins, advanced avionics, and premium passenger amenities.
By Range
Business jets are categorized across different operating ranges, with the 3,000–5,000 nautical mile (NM) category representing a leading range segment.
This range provides a balance between regional and transcontinental connectivity and is suitable for corporate travelers requiring direct access between major business centers.
By Region
-
North America
-
Europe
-
Asia Pacific
-
Middle East and Africa
-
Latin America
North America currently dominates the global business jet market, accounting for 52.4% of revenue in 2025. The region benefits from decades of private aviation infrastructure investment, a high density of registered business aircraft, extensive FBO networks, and a deeply established corporate aviation culture.
Europe represents another significant market, accounting for 22.6% of global revenue. Cross-border executive travel, sports and luxury tourism, and growing adoption of jet-card programs are supporting regional demand.
Asia Pacific holds a 15.8% share and represents the fastest-growing regional market. Increasing UHNWI wealth, expanding aviation infrastructure, corporate expansion, and government initiatives such as India's UDAN regional connectivity program are creating significant opportunities.
The Middle East and Africa account for 5.4%, supported by strong VVIP demand across GCC countries, sovereign wealth-driven travel, and tourism development initiatives including Vision 2030.
Latin America accounts for 3.8%, with demand supported by remote mining and energy operations, UHNWI population growth in Brazil, and near-shoring activity.
Key Regional Insight: North America's Strategic Position
North America's leadership is supported by the United States' extensive private aviation ecosystem. The region benefits from a large network of public-use airports, thousands of FBO facilities, a high concentration of corporate headquarters, and a mature business aviation culture.
The United States alone represents approximately 68% of North America's business jet market. The strong contribution of business aviation to the U.S. economy, combined with widespread corporate adoption and extensive airport connectivity, provides the region with a structural advantage.
Asia Pacific: The Fastest-Growing Regional Market
Asia Pacific represents the fastest-growing regional opportunity, driven by increasing wealth creation, expanding private aviation infrastructure, and rising corporate mobility requirements.
China is investing in business aviation infrastructure across tier-2 cities, while Japan and South Korea are developing business jet connectivity for cross-border corporate travel. India's expanding UHNWI population and regional airport connectivity initiatives are also creating new demand corridors for charter and ownership models.
The combination of increasing wealth, developing infrastructure, and expanding corporate activity is expected to strengthen Asia Pacific's position as a key growth market through 2034.
Business Jet Industry Value Chain
The business jet value chain extends from raw materials and aerospace components to aircraft manufacturing, sales, operations, maintenance, and end-user services.
Raw Materials and Components
Major participants supply carbon fiber, aerospace structural components, engine parts, and other specialized materials required for aircraft manufacturing.
Engine Manufacturing
Engine suppliers include Rolls-Royce, Pratt & Whitney Canada, Honeywell Aerospace, GE Aerospace, and Williams International.
Avionics and Systems
Companies such as Honeywell Aerospace, Garmin, Collins Aerospace, and Thales Group provide avionics, flight management, communications, navigation, and aircraft systems.
Aircraft Manufacturing
Major OEMs include Gulfstream Aerospace Corporation, Bombardier, Textron Inc., Dassault Aviation, Embraer, and Pilatus Aircraft Ltd.
Sales and Distribution
Aircraft are sold through OEM direct sales, authorized dealer networks, fractional ownership platforms, and charter brokers.
Operations and MRO
Major service providers include Jet Aviation, Signature Aviation, and StandardAero, supporting aircraft operations, maintenance, repair, refurbishment, and lifecycle management.
End Users
Key end users include corporate flight departments, charter operators, government and VVIP users, medical airlift services, and high-net-worth individuals.
Technology Landscape in the Business Jet Industry
Advanced Avionics and Flight Management Systems
Next-generation avionics architectures increasingly incorporate integrated touchscreen flight decks, enhanced ground proximity warning systems, ADS-B Out compliance, and AI-assisted flight management capabilities.
Gulfstream's Symmetry flight deck represents this shift toward intuitive cockpit environments designed to reduce pilot workload and improve operational awareness.
Sustainable Aviation Fuel and Hybrid Propulsion
SAF and alternative propulsion technologies are becoming central to the industry's long-term sustainability strategy. Major OEMs and engine manufacturers are working toward 100% SAF-compatible engines and investigating hybrid-electric propulsion.
Rolls-Royce's UltraFan technology represents an example of next-generation propulsion development aimed at improving fuel efficiency and reducing aviation emissions.
Advanced Cabin Connectivity
High-throughput satellite connectivity is increasingly becoming standard across large and super-midsize business jets. New connectivity systems provide high-speed internet capable of supporting professional applications, entertainment, and secure enterprise communications.
The integration of low-Earth-orbit satellite connectivity is further improving the quality and reliability of onboard internet services.
Predictive Maintenance and Digital Twin Technology
AI-driven predictive maintenance systems and digital twin technologies are enabling operators to monitor aircraft health and anticipate potential component failures.
By analyzing real-time engine telemetry, structural sensors, and avionics diagnostics, these technologies can improve maintenance planning, reduce unexpected downtime, and enhance aircraft utilization.
Competitive Landscape in the Business Jet Industry
The global business jet market exhibits a moderately concentrated competitive structure at the OEM level. The top five manufacturers, including Gulfstream Aerospace Corporation, Bombardier, Textron Inc., Dassault Aviation, and Embraer, collectively account for approximately 75–80% of global new aircraft delivery revenue in 2025.
Leading companies are competing through aircraft range, cabin comfort, advanced avionics, connectivity, propulsion efficiency, sustainability, and lifecycle support.
Manufacturers are also investing in SAF-compatible technologies, predictive maintenance platforms, advanced cabin systems, and next-generation aircraft programs to differentiate their offerings.
The aftermarket, charter brokerage, and MRO segments remain considerably more fragmented, with numerous regional operators and maintenance providers competing across international markets.
Key Business Jet Market Players Include
-
Gulfstream Aerospace Corporation
-
Bombardier
-
Textron Inc.
-
Dassault Aviation
-
Embraer
-
Pilatus Aircraft Ltd.
Key Company Profiles
Gulfstream Aerospace Corporation
Gulfstream Aerospace Corporation, a wholly owned subsidiary of General Dynamics headquartered in Savannah, Georgia, is positioned as a global leader in ultra-long-range business jets. Its G700 and G800 platforms represent the company's focus on cabin volume, range, and advanced avionics.
Product Portfolio: G280, G400, G500, G600, G700, G800
Recent Development: In April 2025, Gulfstream's G800 received certification from both the U.S. FAA and EASA, enabling deliveries to customers in North America, Europe, and other global markets.
Strategic Focus: SAF adoption, Symmetry touchscreen avionics, and active-noise-cancellation cabin technology.
Bombardier
Bombardier, headquartered in Montreal, Canada, produces large-cabin and ultra-long-range business jets. Its Global series is positioned within the ultra-long-range segment, while the Challenger family serves large-cabin corporate aviation customers.
Product Portfolio: Challenger 3500, Global 5500, Global 6500, Global 7500, Global 8000
Recent Development: In January 2026, Bombardier announced a C$100 million expansion of its manufacturing footprint in Dorval, Quebec, aimed at increasing business aircraft assembly capacity.
Strategic Focus: Nuage seating technology, Smart Link Plus predictive maintenance, and expansion of its defense business.
Textron Inc.
Textron Inc., through its Cessna Citation and Beechcraft brands, offers a broad range of business aircraft serving corporate flight departments, charter operators, and owner-pilot customers.
Product Portfolio: Citation M2 Gen2, CJ series, XLS, Longitude, Ascend
Recent Development: In April 2022, Textron Aviation announced that flyExclusive had placed an order for up to 30 Cessna Citation CJ3+ light jets.
Strategic Focus: Digital cockpit connectivity, expansion of Citation Service Centers, and owner-pilot training programs.
Market Concentration Analysis
The business jet market demonstrates moderate-to-high concentration at the aircraft manufacturing level, with the five leading manufacturers collectively controlling approximately 75–80% of new aircraft delivery revenue in 2025.
By contrast, the aftermarket services, charter brokerage, and MRO segments remain considerably more fragmented. Numerous regional operators and maintenance companies compete across different geographies and aircraft categories.
Consolidation remains an important industry characteristic, driven by rising certification costs, sustainability investment requirements, and the growing need to provide integrated full-lifecycle services.
Between 2020 and 2025, industry activity included fleet expansions by major charter operators, acquisitions of digital aviation platforms, and consolidation among MRO providers seeking multi-OEM certified capabilities.
Investment & Growth Opportunities
Fastest-Growing Segments
SAF integration and hybrid-electric propulsion programs, AI-powered digital charter booking platforms, and ultra-long-range large-cabin business jets represent some of the highest-growth investment opportunities in the market.
SAF integration and hybrid-electric propulsion programs are estimated to grow at a CAGR of 9.5% through 2034, while AI-powered digital charter booking platforms are projected to grow at 18%. Ultra-long-range large-cabin aircraft platforms are expected to grow at 6.2%.
Emerging Market Expansion
South and Southeast Asia collectively represent an incremental USD 1.8 Billion business jet opportunity by 2034.
Strategic partnerships with regional FBO and charter operators, alignment with national aviation development programs in countries such as India and Indonesia, and deployment of light-to-midsize aircraft fleets represent potential market-entry strategies.
Venture and Institutional Investment Trends
The convergence of urban air mobility and business aviation is attracting institutional investment into eVTOL-to-business-jet intermodal platforms designed to connect city centers with regional business aviation terminals.
Private equity interest also remains elevated in MRO platform consolidation, particularly among full-spectrum maintenance providers with certified capabilities across multiple OEM platforms. The aging global aircraft fleet is expected to continue supporting aftermarket expenditure.
Market Drivers, Challenges & Opportunities
Major Market Drivers
-
Rising Corporate Demand for Time-Efficient Travel: Business jets enable direct city-pair connectivity, reduced travel time, access to secondary airports, and productive cabin environments.
-
Growth of Fractional Ownership and Jet-Card Programs: Flexible ownership and charter models are broadening private aviation access while reducing capital and operational obligations for users.
-
Expansion of Private Aviation Infrastructure: Investment in FBOs, private terminals, hangars, and customs facilities is improving business aviation connectivity.
-
Medical and VVIP Transportation Requirements: Demand for urgent medical airlift, organ transportation, and government travel is creating stable specialized demand.
-
Increasing High-Net-Worth Population: Rising wealth creation across emerging markets is expanding the potential customer base for business aviation.
Key Market Restraints
-
High Acquisition and Operating Costs: Business jets can require capital expenditure ranging from approximately USD 3 million for entry-level light jets to more than USD 60 million for ultra-long-range large-cabin aircraft.
-
Stringent Emission Regulations: ICAO and regional emission standards, including CORSIA, are increasing pressure on manufacturers and operators to accelerate sustainability investments.
-
Geopolitical Risks and Airspace Restrictions: International tensions, airspace closures, and overflight restrictions can complicate route planning and increase operating costs.
Emerging Opportunities
-
Sustainable Aviation Fuel Integration: Increasing regulatory requirements and corporate sustainability commitments are creating significant opportunities for SAF adoption and 100%-compatible aircraft technologies.
-
Emerging Market Expansion: Asia Pacific and Latin America provide substantial incremental market opportunities as private aviation infrastructure and wealth populations expand.
-
Advanced Propulsion: Hybrid-electric propulsion technologies can create opportunities for differentiated aircraft platforms and improved operating economics.
-
Digital Aviation Platforms: AI-powered booking and charter management systems can improve customer access and operational efficiency.
-
Predictive Maintenance: AI-driven aircraft health monitoring and digital twin technologies can reduce maintenance disruptions and support better lifecycle management.
Key Market Challenges
-
Fleet Disposal and Lifecycle Management: End-of-life aircraft disposal and recycling infrastructure remains underdeveloped, creating increasing ESG-related requirements.
-
Regulatory Complexity: Differences among FAA, EASA, CAAC, DGCA, and other aviation authorities create certification challenges and increase development timelines for globally marketed aircraft.
Business Jet Market FAQs
1. What is the current size of the global business jet market?
The global business jet market reached USD 20.62 Billion in 2025 and is projected to reach USD 28.54 Billion by 2034, expanding at a CAGR of 3.49% during 2026–2034.
2. What is driving the growth of the business jet market?
Key growth drivers include rising corporate demand for time-efficient travel, increasing adoption of fractional ownership and jet-card programs, expanding private aviation infrastructure, growing medical and VVIP transportation requirements, and rising demand among high-net-worth individuals.
3. Which region dominates the business jet market?
North America dominates the market, accounting for 52.4% of global revenue in 2025. Its leadership is supported by extensive FBO infrastructure, a high concentration of business aircraft, corporate aviation adoption, and strong private aviation connectivity.
4. Which region is expected to grow the fastest?
Asia Pacific represents the fastest-growing regional market, driven by UHNWI wealth creation, expanding aviation infrastructure, corporate expansion, and initiatives such as India's UDAN regional airport connectivity program.
5. Which business model dominates the business jet market?
The on-demand service segment dominates, accounting for 58.4% of the market in 2025. Flexible charter services and jet-card programs are gaining popularity because they provide access to private aviation without the financial and operational obligations of full aircraft ownership.
6. Which point of sale leads the business jet market?
OEM represents the leading point of sale, accounting for 62.4% of the market in 2025. Demand is supported by customer preference for new-generation aircraft with advanced avionics, modern engines, composite airframes, customization options, warranties, and manufacturer-backed lifecycle support.
7. What are the major trends in the business jet market?
Major trends include increasing adoption of on-demand charter and digital booking platforms, growing SAF adoption, rising demand for long-range ultra-wide-cabin aircraft, advanced avionics and connectivity, and the use of predictive maintenance and digital twin technologies.
Conclusion: Business Jet Market Outlook to 2034
The global business jet market is positioned for sustained growth through 2034, with the market expected to expand from USD 20.62 Billion in 2025 to USD 28.54 Billion by 2034, representing a CAGR of 3.49%.
The market is benefiting from rising corporate demand for time-efficient transportation, increasing adoption of on-demand charter and fractional ownership models, expanding private aviation infrastructure, and growing requirements for medical and VVIP transportation.
Technological innovation is expected to remain a key component of the industry's long-term development. Advanced avionics, high-speed connectivity, predictive maintenance, digital booking platforms, sustainable aviation fuel, and hybrid-electric propulsion are creating new opportunities for manufacturers and operators.
North America is expected to retain its leading position due to its mature private aviation ecosystem and extensive infrastructure, while Asia Pacific is positioned as the fastest-growing region as wealth creation and business aviation infrastructure expand across China, India, Japan, South Korea, and Southeast Asia.
At the same time, high acquisition and operating costs, tightening emissions regulations, geopolitical uncertainty, fleet lifecycle challenges, and complex certification requirements will continue to influence industry strategies.
Companies investing in sustainable propulsion, next-generation aircraft, digital aviation platforms, advanced connectivity, and integrated lifecycle services will be well positioned to capitalize on the evolving business jet market through 2034.
About the Author
IMARC Group is a leading global market research company providing data-driven insights and strategic consulting services across diverse industries. The company delivers comprehensive research reports covering automotive, technology, healthcare, chemicals, packaging, food & beverages, consumer goods, and industrial sectors, helping organizations make informed business decisions and identify emerging growth opportunities.
Media & Sales Contact
IMARC Group
United States: +1-201-971-6302
India: +91-120-433-0800
United Kingdom: +44-753-714-6104

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Portuguese (Brazil)
 Greek
 Bengali